Category Archives: Latest VAT news

VAT – The Future for the EC Digital Single Market

By   11 May 2015

VAT – The Future for the EC Digital Single Market

The EC has announced its plans for its VAT digital single market in respect of online sales. Full details are here and here.

The highlights are:

• Extension of MOSS to intra-EC and third country online B2C sales of goods.

• Introduction of a new EC-wide VAT threshold to help start-up businesses.

• Ending current distance selling thresholds.

• Allowing for domestic controls, including a single audit of cross-border sales.

• Removal of the VAT exemption for the import of small consignments form third countries.

• Removal of barriers to cross-border sales eg; geo-blocking and costs.

This is likely to have a huge impact on the way businesses deal with VAT on sales of goods to individuals overseas. If the introduction of MOSS is anything to go by, we may be in for a bumpy ride.

VAT – Business Entertainment Flowchart. What input tax may I recover?

By   11 May 2015

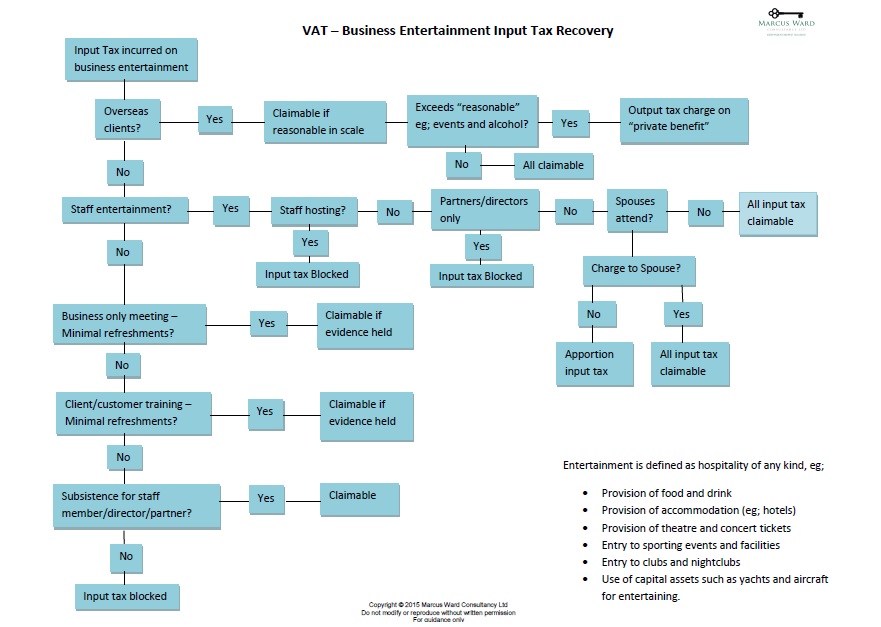
VAT – Recovery of input tax incurred on entertainment

One of the most common questions asked on “day-to-day” VAT is whether input tax incurred on entertainment is claimable.  The answer to this seemingly straightforward question has become increasingly complex as a result of; HMRC policy, EC involvement and case law.  Different rules apply to entertaining; clients, contacts, staff, partners and directors depending on the circumstances.  It seems reasonable to treat entertaining costs as a valid business expense.  After all, a business, amongst other things, aims to increase sales and reduce costs as a result of these meetings.  However, HMRC sees things differently and there is a general block on business entertainment.  It seems like HMRC does not like watching people enjoying themselves at the government’s expense!

If, like me, you think in pictures, then a flowchart may be useful for deciding whether to claim entertainment VAT.  It covers all scenarios, but if you have a unique set of circumstances or require assistance with some of the definitions, please contact me.

I thank my friend and colleague Leila Ong for help with this, and also with the series of presentations we have recently carried out and which, amongst other subjects, covered business entertainment. Should you require VAT training or presentations, don’t forget our comprehensive service here which can be tailored to your needs.

VAT -Business Entertainment Flowchart

Business Entertainment flow chart

Download here: VAT Business Entertainment Input tax recovery flowchart

VAT- Is the Upper Tribunal bound by High Court decisions?

By   6 May 2015

Upper Tribunal versus High Court

In the recent case of Meena Seddon Settlement which involved Inheritance Tax, the First Tier Tribunal (FTT) was required to decide whether the Upper Tribunal is bound by decisions made in the High Court. The FTT decision will doubtless affect VAT cases in the future.

It decided to follow a precedent set by the Upper Tribunal over an earlier decision by the High Court.

The taxpayer contended that the matter should be decided on the basis of a previous High Court decision. HMRC argued on the basis of a later Upper Tribunal decision. In normal circumstances, a later decision should take precedence over the earlier if both decisions have the same authority and have fully considered the previous judgments. However, if the taxpayer was correct to say that the Upper Tribunal was bound by precedents set by the High Court, the later decision could be disregarded as being wrong in law.

The FTT decided that it was the intention of Parliament that the Upper Tribunal was not bound to follow High Court precedents. This was notwithstanding the fact that a High Court could have a supervisory role over the Upper Tribunal in cases of judicial review. Therefore, it determined the case on the authority of the later Upper Tribunal decision in favour of HMRC.

VAT – Compound or multiple supplies? Latest from the courts

By   17 March 2015

In Colaingrove Limited the Upper Tribunal (UT) this week was required to decide whether the supply of electricity to a mobile home was an independent supply, or just one element of part of an overall supply of holiday accommodation.

This is a notoriously difficult area of VAT as the recent case of WM Morrison Supermarket Limited (“Morrisons”) demonstrates.  In this case disposable barbecues (standard rated) were sold with charcoal (reduced rated when sold independently) and the UT decided that it was not possible to carve out the reduced rated element form the overall supply so the whole supply was standard rated.

In Colaingrove a flat-rate charge was made to holidaymakers who paid it as part of the hire charge for self-catering accommodation in mobile homes.  The appellant argued that the electricity charge was separately identifiable and quantifiable and should consequently be treated as a reduced rated (5% rather than 20%) independent supply.

The logic in Morrisons was applied in this case and the UT ruled that the charge for the electricity should properly be included in the price of the standard rated holiday accommodation.  The charge should not be split out, so the entire charge for the accommodation was standard rated, including the specified sum charged for the electricity.

The judge acknowledged that this case was not an easy one to decide and that the arguments advanced on behalf of the taxpayer were both powerful and attractive. It would seem likely that an appeal to the Court of Appeal will be made.

This case further illustrates that care must be taken when analysing the VAT treatment of supplies.  There is significant case law on this matter, but there still remains a certain overlap and sometimes conflicting opinions.  The precise facts of the matter are very important when determining whether supplies are compound or multiple for VAT purposes.

Overview

Whether there is a compound or multiple supply is determined by the tests set out in the Card Protection Plan case, namely; firstly, whether there is a principal element of the supply to which all other parts are ancillary and, secondly, whether, in the eyes of the customer, the ancillary element provides a means of better enjoying the principal element. If the answer to both of these questions is yes, then there is a single supply.

VAT – Are e-books books? Update on ECJ’s decision 5 March 2015

By   5 March 2015

Books are zero rated for VAT purposes, but only (currently) if they are of the traditional dead tree variety. The zero rating does not extend to e-books which are standard rated for VAT. There has been a long standing argument between EC Member States (and between other interested parties) that similar content should not be taxed at different rates solely depending on the method of delivery. This argument is about to be tested in the courts. The UK is not permitted by the EC to extend its current zero rating for printed matter, however, it is expected that the contention in this case will be that the inclusion of new products will not extend the zero rating, but rather the development of technology has created a supply that should be covered by the existing zero rating legislation.

If it is accepted by the courts that all types of book should attract the same rate of VAT, it may mean that the rate will be equalised upwards. So, by the end of the year we could be looking at VAT of 5% being added to books, newspapers and other printed matter which was hitherto VAT free – A “tax on learning” as previous protests had it when there was a threat to tax free books.

UPDATE

The European Court of Justice (ECJ) has today ruled that France and Luxembourg must raise their reduced VAT rates on sales of  e-book. This will conclude ongoing disputes (see above) between EC countries over whether e-books may be treated similarly to printed books at the nil or reduced rates.  The UK and Germany were the main protagonists in challenging those Member States where e-books have been treated the same as printed versions.

Initially, Luxembourg and France began reclassifying e-books at the same rate as printed books – 3% and 5.5% in 2012. Subsequently, Italy and Malta joined them at the start of 2015, reducing the rates to 4% and 5%.

These rates where challenged by the UK and Germany who asked the EC to impose rules to ensure that e-books could not take advantage of the printed book rates.  Today, the ECJ published its ruling, stating that since e-books do not have the same physical characteristics as printed books and therefore cannot benefit from the printed book reduced VAT rules.

This decision does seem to go against common sense,but the ECJ’s hands were somewhat tied by the VAT rules which were introduced before e-books existed.

VAT – Domestic legislation versus EC law – a new case

By   4 March 2015

In the recent case of VDP Dental Laboratory NV & ors (C-144/13) the ECJ has decided that a Dutch exemption for a supply which is ultra vires in respect of EC VAT legislation does not give a right to input tax deduction via EC legislation.  The exemption precludes input VAT recovery, but has the effect of exempting imports and acquisitions into The Netherlands. The ECJ held that a taxable person who is not obliged to charge VAT on the supply of goods because national law (in contravention of Community law) provides for exemption, cannot however, rely on Community law to claim input tax deduction of VAT incurred on purchases incurred in respect of that supply.  What this means though is that the exemption in Dutch domestic legislation means that the taxpayer will not be taxed on importations or acquisitions, irrespective of the VAT treatment in the Member State of an EU supplier.

Broadly, this means that a business cannot take advantage of domestic legislation and/or EC law in circumstances where it may benefit.

VAT on residential developments

By   20 February 2015

Should work on existing residential property have the same VAT treatment as new build housing? 

The UK cannot create a new zero rate, however, should, say, the reduced rate apply to extensions/redevelopment?

And if so, where should the line be drawn?

Article from Property Week here

VAT – Prompt Payment Discounts (PPD) changes to valuation from 1 April 2015

By   19 February 2015

VAT – Prompt Payment Discount Changes

Businesses don’t have much time to change their accounting procedures and systems to deal with the new PPD rules.  A recent survey has shown that over 13% of business will be affected by the changes which do not appear to have been given much publicity. These changes are necessary to align UK legislation with the EC Principal VAT Directive.  It is crucial that advisers and businesses are not caught out by the change in valuation of supplies offered at a discount.

The changes – summary

Old Rules

Under the previous rules output tax was due on the discounted price offered for prompt payment – regardless of whether the customer takes up the discount.

New Rules

From 1 April 2015 output tax is due on the full consideration actually paid by the customer when PPD is offered.

The new rules are required because HMRC is concerned that there was a difference between output tax paid on the discounted price, and the (higher) amount received if a PPD is not taken.  Historically, this was not so much of an issue because most PPD was offered B2B and the VAT was generally recoverable by the recipient of the supply.  However, increasingly, PPD is now offered B2C and therefore reduces “sticking tax” and the consequential VAT loss for HMRC.

A simple example

Old Rules

B2B PPD of 10% if invoice paid within 21 days.

Goods                                          £10,000

VAT 20% on £9,000                     £1,800

Invoice Total                               £11,800

Both parties post £1,800 to VAT account and there is no adjustment if discount not taken.

New Rules

Using the above figures:

Must assume discount is not taken so invoice total = £12,000

If customer actually takes up PPD a credit note is issued for both elements of the supply – £200 credit for the VAT.

Both parties process the new documentation to adjust the original invoice – VAT is neutral.

This increases a business’ administrative burden and also creates a significant additional risk of penalties and interest if businesses are ignorant of the change, or implement the changes incorrectly.

VAT Penalties: A Discussion Document by HMRC

By   11 February 2015

A discussion document is seeking views by 11 May about potential improvements to how HMRC applies penalties for failing to pay what is owed or to meet deadlines for returns or registration.

As HMRC designs a tax system for the modern, digital world, it wants to ensure that its approach to penalties also keeps up to date with both technology and behavioural science. HMRC is considering whether and how it should differentiate between those who deliberately and persistently fail to meet administrative deadlines or to pay what they should on time, and those who make occasional and genuine errors for which other responses might be more appropriate.

HMRC is looking for feedback from individuals and businesses. The purpose of the discussion is to seek views on the policy design and any suitable possible alternatives, before consulting later on a specific proposal for reform.

I look at the main points below and identify where changes to the penalty system are most likely to be made.

The document may be accessed here:

https://www.gov.uk/government/uploads/system/uploads/attachment_data/file/400211/150130_HMRC_Penalties_a_Discussion_Document_FINAL_FOR_PUBLICATION__2_.pdf

 Summary

In terms of Indirect Tax there are two main areas which HMRC is focussing on:

VAT default surcharge – HMRC highlights two issues with the current VAT default surcharge regime. The first is the concern that while the absence of penalty for the initial offence in a 12 month period gives business the chance to get processes right, some customers simply ignore this warning.

The second concern is the issue of proportionality which fails to distinguish between payments that are one or two days late or many months late.

 Excise regulatory penalties – This also considers proportionality, noting that regulatory failures can lead to very large penalties, because the penalty is fixed as a percentage of the duty. The size of such penalties might be viewed as disproportionate.

The existing, long-standing default surcharge regime has always had issues with the principle of proportionality.  The regime has been challenged in the Courts –  notably in the Trinity Mirror Plc case (soon to be heard at the UT) where the earlier FTT allowed the appeal against a default surcharge on the grounds of proportionality.

If you would like assistance in making a representation please contact me.

VAT – Splitting a business to avoid registration doesn’t work

By   30 January 2015

I have a cunning plan to avoid registering for VAT…….

….I’ll simply split my business into separate parts which are all under the VAT registration turnover limit – ha!

I’ve heard this said many a time in “bloke in the pub” situations. But is it possible?

You will not be surprised to learn that HMRC don’t like such schemes and there is legislation and case law for them to use to attack such planning known as “disaggregation”. This simply means artificially splitting a business.

What HMRC will consider to be artificial separation:

HMRC will be concerned with separations which are a contrived device set up to circumvent the normal VAT registration rules. Whether any particular separation will be considered artificial will, in most cases, depend upon the specific circumstances. Accordingly it is not possible to provide an exhaustive list of all the types of separations that HMRC will view as artificial. However, the following are examples of when HMRC would at least make further enquiries:

Separate entities supply registered and unregistered customers

In this type of separation, the registered entity supplies any registered customers and the unregistered part supplies unregistered customers.

Same equipment/premises used by different entities on a regular basis

In this type of situation, a series of entities operates the same equipment and/or premises for a set period in any one-week or month. Generally the premises and/or equipment is owned by one of the parties who charges rent to the others. This situation may occur in launderettes and take-aways such as fish and chip shops or mobile catering equipment.

Splitting up of what is usually a single supply

This type of separation is common in the bed and breakfast trade where one entity supplies the bed and another the breakfast. Another is in the livery trade where one entity supplies the stabling and another, the hay to feed the animals. There are more complex examples, but the similar tests are applied to them too.

Artificially separated businesses which maintain the appearance of a single business

A simple example of this type of separation includes; pubs in which the bar and catering may be artificially separated. In most cases the customer will consider the food and the drinks as bought from the pub and not from two independent businesses. The relationship between the parties in such circumstances will be important here as truly franchised “shop within a shop” arrangements will not normally be considered artificial.

One person has a controlling influence in a number of entities which all make the same type of supply in diverse locations

In this type of separation a number of outlets which make the same type of supplies are run by separate companies which are under the control of the same person. Although this is not as frequently encountered as some of the other situations, the resulting tax loss may be significant.

The meaning of financial, economic and organisational links

Again each case will depend on its specific circumstances. The following examples illustrate the types of factors indicative of the necessary links, although there will be many others:

Financial links

  • financial support given by one part to another part
  • one part would not be financially viable without support from another part
  • common financial interest in the proceeds of the business

Economic links

  • seeking to realise the same economic objective
  • the activities of one part benefit the other part
  • supplying the same circle of customers

Organisational links

  •  common management
  • common employees
  • common premises
  • common equipment

HMRC often attack structures which were not designed simply to avoid VAT registration, so care should be taken when any entity VAT registers, or a conscious decision is made not to VAT register. Registration is a good time to have a business’ activities and structure reviewed by an adviser.

As with most aspects of VAT, there are significant and draconian penalties for getting registration wrong, especially if HMRC consider that it has been done deliberately to avoid paying VAT.