Category Archives: Penalties

VAT treatment of cryptoassets – new HMRC guidance

By   19 October 2026
Following our previous articles on cryptoassets, HMRC has published a document: Help with VAT treatment of cryptoassets — GfC2. 
This guidance sets out:
  • what HMRC means by cryptoassets
  • when a business needs to register
  • what information a business need to collect about your customers – and why
  • the rules about the place of supply for cryptoasset transactions
  • what records digital platforms and marketplaces need to keep
It is aimed at UK and overseas businesses involved in cryptoasset transactions where UK VAT may apply. It includes businesses that sell or exchange cryptoassets and businesses that operate platforms where other people do so.

Overview
Cryptoassets (sometimes called ‘tokens’ or ‘cryptocurrencies’) are a digital representation of value that are created, stored and transferred securely using public computer networks, and cannot be altered or destroyed.
There are many different types of tokens, and they can have different uses. Some tokens can represent ownership of something or the right to access particular goods or services. The asset, goods or services represented by the token are known as the underlying asset or supply. The underlying asset can be tangible or intangible, such as digital or physical art, music and collectables.
A non-fungible token (NFT) is a unique digital certificate that represents ownership of an asset. The VAT treatment of an NFT will depend on the asset it represents. For example, if the underlying asset is a piece of digital art, then the same VAT treatment as digital art will usually apply. If the underlying asset is a physical item, such as a car, then the same VATtreatment as a car will usually apply.
It is worth emphasising that there are no separate VAT rules for cryptoassets. VAT still depends on what you supply and how it is used, not the definition or description of a token
HMRC says that following these guidelines will help taxpayers reduce the risk of mistakes, VAT adjustments and penalties.

HMRC new ‘VAT Assist’ service

By   5 October 2026
VAT Assist
HMRC has announced a VAT Assist service which is due to be launched in April 2027.
The service will compare data added to a taxpayer’s VAT return against information HMRC holds for that business to provide incisive feedback to help businesses submit accurate tax returns.
The service will be available to businesses using participating third-party software and HMRC will monitor and review the relevance and effectiveness of the feedback provided.
The pre-submission VAT Return data is transmitted from third-party software to HMRC via an API. That data is analysed in real time, using a rule-based model, comparing to data held within HMRC. Where potential errors are identified, digital ‘nudges’ will be transmitted through the API for the third-party software to present to the taxpayer. 
The message will be displayed to the taxpayer through their software before the return is submitted although the taxpayer is not required to act on the feedback and may proceed with their submission if they consider that the return is correct. 

VAT: Electronic sales suppression (ESS) compliance checks

By   8 September 2026
HMRC has published a new Factsheet CC/FS68A which provides information on electronic sales suppression (ESS). It explains the powers HMRC can use to help it identify and tackle ESS. It also explains the penalties which may be levied if a person is in possession of an ESS tool.
More details on ESS and ESS tools here. 

HMRC powers

Finance Act 2022, Schedule 14 allows HMRC to issue an information notice for ESS. This means HMRC can ask for certain information that applies to ESS. It allows the issue of a Notice to a ‘relevant person’ for a ‘relevant purpose’.

Relevant Person

A ‘relevant person’ is any person who HMRC think may be liable to a penalty for being involved in ESS.

Relevant purpose

A ‘relevant purpose’ is the reason HMRC is asking for information about ESS and ESS tools.

The law allows HMRC to do this in three situations. These are to help HMRC:

  • decide whether a relevant person has made, supplied, promoted, or possesses an ESS tool and whether this person is liable to a penalty
  • understand how the ESS tool works
  • identify any other person who has made, supplied, promoted, or possesses the ESS tool. 

VAT: What is a taxable supply? – Definition

By   8 September 2026

VAT Basics

Taxable supply

It is sometimes useful when considering a transaction to “go back to basics” for VAT purposes. There are certain tests to determine whether a supply is taxable, and these are set out below. Broadly, the tests establish whether UK VAT is payable on a sale and they determine whether an entity is “in business”, that is; carrying on an economic activity.

A transaction is within the scope of UK VAT if all four of the following conditions are satisfied:

  • It is a supply of goods or services.

There is a distinction between the two types of supply as different VAT treatments may apply.  Generally, everything that is not tangible goods is services. However, if no goods or services are actually provided, there is no supply.  Indeed, if there is no consideration for a supply, in most cases it is not a taxable supply.

  • It takes place in the UK.

There are quite complex tests to consider when analysing the “place of supply”, especially where services are concerned.  If the place of supply is outside the UK then usually no UK VAT is due, however, the supply may be subject to VAT in another country.

  • It is made by a taxable person.

A taxable person is any legal entity which is, or should be, registered for VAT in the UK.

  • It is made in the course or furtherance of any business carried on by that person

Business

The term “business” is only used in UK legislation, The Principal VAT Directive refers to “economic activity” rather than “business” and since UK domestic legislation must (well historically) conform to the Directive both terms must be seen as having the same meaning.  Since the very first days of VAT there have been disagreements over what constitutes a “business”. I have only recently ended a dispute over this definition for a (as it turns out) very happy client. The tests were set out as long ago as 1981 and may be summarised as follows:

  • Is the activity a serious undertaking earnestly pursued?
  • Is the activity an occupation or function, which is actively pursued with reasonable or recognisable continuity?
  • Does the activity have a certain measure of substance in terms of the quarterly or annual value of taxable supplies made (bearing in mind that exempt supplies can also be business)?
  • Is the activity conducted in a regular manner and on sound and recognised business principles?
  • Is the activity predominantly concerned with the making of taxable supplies for a consideration?
  • Are the taxable supplies that are being made of a kind which, subject to differences of detail, are commonly made by those who seek to profit from them?

So, if these tests are passed a taxable supply exists. The next step is to establish which VAT rate applies. In an often quoted comment from the judge in the Morrison’s Academy Boarding Houses Association 1978 STC1 Court Of Session case “…In my opinion it will never be possible or desirable to define exhaustively ‘business’ ”. Which what it lacks in helpfulness, makes up for in candour.

There was something of a deviation from the Lord Fisher tests in the Longbridge Court of Appeal case, however, that appears to be a blip and HMRC seem to have reverted to Lord Fisher in subsequent hearings on the same topic. A bit of a: watch this space area of VAT.

Recent cases on business

Recent case law on this issue here and here and HMRC Internal guidance on the Lord Fisher tests here

Commentary

Tip: It is often easier to consider what isn’t a taxable supply to establish the correct VAT treatment.  Specific examples of situations which are not taxable supplies are; donations, certain free supplies of services, certain grants or funding, some compensation and some transactions which are specifically excluded from the tax by legislation, eg; transfers of going concerns (TOGC).

I think that it is often the case that the basic building blocks of the tax are overlooked, especially in complex situations and I find it helps to “go back to the first page” sometimes.

VAT – Residential Property Triggerpoints

By   24 August 2026

What to look out for

VAT and property transactions are uneasy bedfellows at the best of times.  Getting the tax wrong, or failing to consider it at all can result in a loss of income of 20% on a project, or forgoing all input tax incurred on a development. Even a simple matter of timing can affect a transaction to a seller’s detriment. Here I take a brief look at issues that can impact residential property transactions.  It is important to recognise when VAT may affect a project so I hope that some of these triggerpoints may prove useful.

General points

The following are very general points on residential properties. No two cases are the same, so we strongly recommend that specific advice is obtained.

Refurbishing “old” residential properties

Broadly speaking, the VAT incurred on such work is not reclaimable as the end use of the property will be exempt (either sale or rent). There is no way round this as it is not possible to opt to tax residential dwellings. It may be possible to use the partial exemption de minimis limits if there are any other business activities in the same VAT registration. If this is the only activity of a business, it will not even be permitted to register for VAT. There are special rules if the number of dwellings change as a result of the work (see below).

New residential builds

The first sale (or the grant of a long lease 21 years plus) of a newly constructed dwelling by “the person constructing” is zero rated. This means that any VAT incurred on the construction is recoverable. Care should be taken if the new dwelling is let on a short term basis rather than/before being sold as this will materially affect input tax recovery.  Advice should always be taken before such a decision is made as there is planning available to avoid such an outcome. VAT incurred on professional and legal costs of the development may also be recovered such as; architects, solicitors, advisers, agents etc. VAT registration is necessary in these cases and our advice is to VAT register at the earliest stage possible.

The construction of new dwellings is zero rated, along with any building materials supplied by the contractor carrying out the work.  The zero rating also extends to sub-contractors.  It is not necessary for a certificate to be provided in order to zero rate such building works.

Conversions

There are special rules for refurbishments which create a different number of dwellings (eg; dividing up a single house into flats, or changing the total number of flats in a block, or making one dwelling by amalgamating flats). Generally, it is possible for contractors to invoice for their building work at the reduced rate of 5%. This rate may also apply to conversions. A conversion is defined as work undertaken on a non-residential property, such as a barn, office or church, into one or more self-contained dwellings.  Once converted the sale of the residential property will be zero rated and all of the input tax incurred on associated costs is recoverable (similar to a new build).

Renovation of empty residential premises

Reduced rating at 5% is also available for the renovation or alteration of empty residential premises. Such a premises is one that has not been lived in during the two years immediately before the work starts. HMRC will insist on documentary evidence that the property has been empty for that time.

Purchase of a commercial property intended for conversion

If it is intended to convert a commercial property into residential use and the vendor indicates that (s)he will charge VAT (as a result of the option to tax having been exercised) it is possible for the purchaser to disapply the option to tax by the issue of a certain document; form VAT 1614D. This means that the sale will become exempt.  Advice should always be sought on this issue by parties on each side of the transaction as it very often creates difficulties and significant VAT and other costs (mainly for the vendor).

Mixed developments

If what is being constructed is a building that is only in part a zero-rated dwelling, a contractor can only zero-rate its work for the qualifying parts. For example, if a building  containing a shop with a flat above is constructed, only the construction of the flat can be zero-rated. An apportionment must be made for common areas such as foundations and roof etc. The sale of the residential element when complete is zero rated and the sale of the commercial part will be standard rated if under three years since completion.  If the commercial part is over three years old at the date of sale, or is rented rather than sold, the supply will be exempt with the option to tax available – details here.  If an exempt supply is made, the recovery of input tax incurred on the development will be compromised and it is important that this recognised and planning put in place to avoid this outcome.

DIY building projects

There is a specific scheme for DIY Housebuilders to recover input tax incurred on the construction of a dwelling for the constructor to live in personally.  Details here https://www.marcusward.co/?s=diy

Sale of an incomplete residential development

There are two possible routes to relief if a project is sold before dwellings have been completed (either new build or conversion).  This can often be a complex area, however, there is some zero rating relief which may apply, and also it may be possible to apply TOGC (Transfer Of a Going Concern) treatment to the sale.  In both cases, it is likely that input tax previously claimed by the developer should not be jeopardised.

Overview

There are VAT complications for the following types of transactions/developments and issues:

  • definition of a dwelling
  • arrangements where consortiums or syndicates are used/profit share
  • transactions in connection with nursing or children’s homes or similar
  • “granny flats” in the garden of existing houses
  • work on charitable buildings/ for charities
  • converting specific commercial property into residential property – particularly ex-pubs
  • sales to Housing Associations
  • sales of “substantially reconstructed protected buildings”
  • buying VATable buildings
  • date of completion – zero rating cut off
  • supplies by members of VAT groups
  • definition of building materials
  • input tax on white goods and similar
  • alterations for people with disabilities
  • garages with dwellings
  • land supplied with a property
  • buying property with existing, continuing leases
  • beneficial owner versus legal owner issues
  • change of intention (buying land/property with the intention of using it for one purpose, but the intention changes after purchase)
  • where professional/architect’s fees are incurred
  • planning gains
  • own use of a property
  • mobile homes
  • reverse premiums/surrenders/reverse surrenders re; leases
  • holiday lets and
  • hotels
  • business use by purchaser/tenant
  • contract stage of a property purchase where VAT is potentially chargeable by vendor
  • timing of supplies
  • work re; schools, churches, village halls, hospitals, or any other “unusual” structures

This list is not exhaustive, but I hope it gives a broad idea of where VAT needs to be considered “before the event”. As always, we are available to assist.

VAT: Consignment and call-off stock

By   15 June 2026

VAT basics

Consignment, call-off stock, and sale or return goods

If a business is required to provide regular sales of goods to customers, a prudent business structure is to keep inventory in a warehouse near the customer, or which belongs to the customer. This is likely to reduce transport costs and provides quicker access to the goods thus reducing time in the supply chain.  There are specific VAT rules for businesses which hold stock in foreign countries. They stipulate when, and what VAT should be charged, and if a business needs to VAT register as a non-resident trader in another country in which it is warehousing its goods.

Below we consider what the terms mean, the differences and the VAT treatment applicable.

Differences 

There is often confusion over the terms; consignment and call-off stock, and they are sometimes used interchangeably. They are differentiated based on who controls access to, and use of, the goods. The difference determines the VAT requirements and compliance rules, so it is important to identify the actual arrangements a business has in place, or plan for the most beneficial outcome. Both of these measures involve the transfer of a business’ own goods – for the purposes of this article; cross-border. The transfer of goods within the same legal entity from one country to another is a deemed supply. This fact is sometimes missed, which can lead to problems.  The VAT rules differ from country to country and create legal uncertainty for businesses. 

In summary

  • Consignment stock

Consignment stocks are created when a business transfers its own goods to another Member State to create a stock over which it has control and from which it makes supplies. Typically, there are multiple potential customers for consignment stock.

Note: Goods sent to an overseas customer on sale or return are treated in the same way as consignment stocks.

  • Call-off stock

Call-off stock is the transfer of goods by a business from one Member State to another to create a stock of goods from which its customers can ‘call-off’ ie; use and pay for the goods as and when they require them.

Not call-off stock

Goods delivered to storage facilities operated by the supplier, rather than the customer, should be treated as consignment stocks (see above). If stocks of goods are dispatched by a supplier for call-off by more than one customer, this is also likely to be consignment stock.

VAT treatment

Consignment stock

There is an initial deemed supply of own goods to form the stock which takes place in the country from which the goods are originally shipped. This is usually VAT free as a dispatch and the usual documentary requirements apply.

The place of subsequent supplies of the goods, once a buyer has been found (change of ownership) is usually the country in which the stock is held.

Because the business is transferring its own goods “to itself” in another country it will be making an acquisition of goods in that country. The business is likely to be liable to register for VAT there (or appoint a fiscal representative in the country of arrival) and be responsible for import obligations in the other country. Output tax will also be due (at the rate of VAT applicable in the country in which the goods are located) on the sale to a third party.

Consignment stock – reporting requirements

If a UK VAT registered business transfers goods to another country to create a consignment stock it must complete box 6 on the VAT return reporting a value based on the cost of the goods – see HMRC Public Notice 725. 

Call-off stock

As the customer has control of the goods in storage, is aware of stock movements, and may take stock whenever he requires this does not generally require the seller to VAT register in the foreign country as a non-resident trader. Such sales are treated as a “regular’ export and the seller is required to show the customer’s VAT number etc on invoices and other documentation in order to treat it as VAT free in the usual way. The time of supply for these supplies is the date the goods are called off by the customer. 

Call-off stock – reporting requirements 

The supply of call-off stock from the UK to a VAT registered business in another country is VAT free (subject to the normal rules). Box 6 of the VAT return should be completed using a value based on the cost of the goods as above.

The penalty regime…the dark side of VAT

By   29 April 2026
VAT Penalties

I have made a lot of references to penalties in other articles over the years. So I thought it would be a good idea to have a closer look; what are they, when are they levied, rights of appeal, and importantly how much could they cost if a business gets it wrong?

Overview

Broadly, a penalty is levied if the incorrect amount of VAT is declared, either by understating output tax due, or overclaiming input tax, or accepting an assessment which is known to be too low.

Amount of penalty

HMRC detail three categories of inaccuracy. These are significant, as each has its own range of penalty percentages. If an error is found to fall within a lower band, then a lower penalty rate will apply. Where the taxpayer has taken ‘reasonable care,’ even though an error has been made, then no penalty will apply.

  • An error, when reasonable care not taken: 30%;
  • An error which is deliberate, but not concealed: 70%;
  • An error, which is deliberate and concealed: 100%.

Reasonable care

There is no definition of ‘reasonable care’. However, HMRC have said that they would not expect the same level of knowledge or expertise from a self-employed person, as from a large multi-national.

HMRC expect that, where an issue is unclear, advice is sought, and a record maintained of that advice. They also expect that, where an error is made, it is adjusted, and HMRC notified promptly. They have specifically stated that merely to adjust a return will not constitute a full disclosure of an error. Therefore, a penalty may still be applicable.

Notification
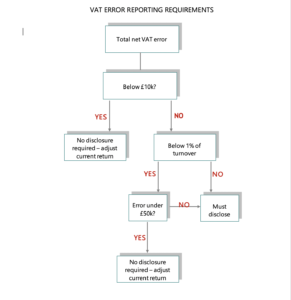
Further, where there is an ‘unprompted disclosure’ of the error, HMRC have power to reduce the penalty further. This measure is designed to encourage businesses to review their own VAT returns.

A disclosure is unprompted if it is made at a time when a person had no reason to believe that HMRC have discovered or are about to discover the inaccuracy. The disclosure will be treated as unprompted even if at the time it is made, the full extent of the error is not known, as long as fuller details are provided within a reasonable time.

What the penalty is based on

The amount of the penalty is calculated by applying the appropriate penalty rate (above) to the ‘Potential Lost Revenue’ or PLR. This is essentially the additional amount of VAT due or payable, as a result of the inaccuracy, or the failure to notify an under-assessment. Special rules apply where there are a number of errors, and they fall into different penalty bands.

Defending a penalty

The percentage penalty may be reduced by a range of ‘defences:’

– Telling; this includes admitting the document was inaccurate, or that there was an under-assessment, disclosing the inaccuracy in full, and explaining how and why the inaccuracies arose;

– Helping; this includes giving reasonable help in quantifying the inaccuracy, giving positive assistance rather than passive acceptance, actively engaging in work required to quantify the inaccuracy, and volunteering any relevant information;

– Giving Access; this includes providing documents, granting requests for information, allowing access to records and other documents.

HMRC have included a provision whereby a penalty can be suspended for up to two years. This will occur for a careless inaccuracy, not a deliberate inaccuracy. HMRC will consider suspension of a penalty where, given the imposition of certain conditions, the business will improve its accuracy. The aim is to improve future compliance and encourage businesses which genuinely seek to fulfil their obligations.

Appealing a penalty 

HMRC have an internal reconsideration procedure, where a business should apply to in the first instance. If the outcome is not satisfactory, the business can pursue an appeal to the First Tier Tribunal. A business can appeal on the grounds of; whether a penalty is applicable, the amount of the penalty, a decision not to suspend a penalty, and the conditions for suspension.

The normal time limit for penalties to four years. Additionally, where there is deliberate action to evade VAT, a 20 year limit applies. In particular, this applies to a loss of VAT which arises as a result of a deliberate inaccuracy in a document submitted by that person.

These are just the penalties for making “errors” on VAT returns. HMRC have plenty more for anything from late registration to issuing the wrong paperwork.

Even darker

There are even more severe penalties for deliberate acts, including significant terms of imprisonment. That is the subject of another article.

Assistance

My advice is always to check on all aspects of a penalty and seek assistance for grounds to challenge a decision to levy a penalty. We have a very high success rate in defending businesses against inappropriate penalties.  It is always worth running a penalty past us.

VAT: Crowdfunding – What is taxable?

By   9 April 2026
What is crowdfunding?

Crowdfunding is the practice of funding a project or venture by raising many small amounts of money from a large number of people, typically via the internet on specifically designed platforms and is an alternative to traditional ways of raising finance. The model is usually based on three parties: the project initiator who proposes the idea or project to be funded, individuals or groups who support the idea, and a moderating organisation (the “platform”) that brings the parties together to launch the idea.

Crowdfunding is a major, growing source of funding for startups, charities, and creative projects, with the global market predicted to grow annually by around 15% from 2026 to 2033 with platforms like Kickstarter, Seedrs, Crowdcube, and GoFundMe being major players.

VAT Treatment

The VAT treatment of supplies that might potentially be made is no different to similar financing arrangements, for example; sponsorship, donations and investments made through more traditional routes. Whether a recipient of crowdfunding is liable to charge and pay VAT depends on the facts in each case.

Examples

Donations

  • where nothing is given in return for the funding, it will be treated as a donation and not liable to VAT – the position is the same where all that the funder receives is a bare acknowledgement, such as a mention in a programme or something similar

Goods and/or services

  • where the funder receives goods or services that have a real value associated with them, for example; clothing, tickets, DVDs, film viewings, output tax will be due

Combination

  • where the payment is for a combination of the two examples above, if it is clear that the donation element is optional then that part of the sponsorship can be treated as a non-taxable donation and the supply will be taxable. If a donation element cannot be carved out, it is likely that all of the payment will be considered as VATable

Investment

  • where the funding takes the form of an investment where the funder is entitled to a financial return such as; interest, dividends or profit share, any payment due to the funder is unlikely to be liable to output tax, The reason why most of these arrangements are outside the scope of VAT is that the provision of capital in a business venture is not seen as a supply for VAT purposes

Royalties

  • if the arrangement is that the funder receives royalties based on a supply of intellectual property or some other similar benefit the payment is likely to be consideration for a taxable supply and output tax will be due

Loan-based 

  • Individuals lend money to businesses or people for interest payments. The making of any advance or the granting of any credit is exempt.

VAT registration 

If income from the sources above which are deemed to be subject to VAT exceeds the VAT registration limit (currently £90,000 in any twelve-month period) the person, in whichever legal identity, such as; individual, company, partnership, Trust etc will be liable to register for VAT. If income is below this limit, it will be possible, but not mandatory to VAT register. The benefits of voluntary registration here.

Input tax recovery

If VAT registered, any input tax incurred on costs relating to crowdfunding is usually recoverable (see here for exceptions). However, if the costs relate to donations or some types of investment then input tax claims are specifically blocked as they would relate to non-business activities. If exempt supplies are made, attributable input tax is generally blocked unless it is de minimis. 

Commentary

There can be difficulties in establishing the tax liability of crowdfunding and in a broader sense “sponsorship” in general. However, experience insists that the biggest issue is initially identifying that there may be a VAT issue at all. If you, or your clients are involved in crowdfunding, or have sponsors, it would be prudent to review the VAT treatment of the activities.

VAT: New, important HMRC guidance for zero-rating exports

By   10 March 2026

HMRC has updated its Notice 703 which explains the conditions for VAT zero-rating exports of goods. It is crucial for a business to have the correct documentation to evidence goods physically moving out of the UK. 

Information on official evidence has been updated in paragraphs 6.2, 7.1 and 7.2 as follows:

  • Para 6.2 Official evidence

Official evidence is an export declaration for the goods submitted to the Customs Declaration Service which has generated a departure confirmation. You will need the Movement Reference Number (MRN) or Declaration Unique Consignment Reference (DUCR) of the declaration. 

  • Para 7.1 Air and sea freight 
  • If you are using commercial transport documents as proof of export for goods exported outside the UK or EU by:
    • air — you must obtain and retain an authenticated basic master airway bill or house air waybill endorsed with the flight prefix and number, and the date and place of departure
    • sea — you must keep one of the copies of the bill of lading or sea waybill along with a note of the export declaration Movement Reference Number (MRN) or Declaration Unique Consignment Reference (DUCR) or, where a shipping company does not issue these, a certificate of shipment (certifying actual shipment) along with a note of the export MRN or DUCR, given by a responsible official of that company.
  • 7.2 Road freight

    The international consignment note provides evidence of the identity of the contracting parties when goods are transferred by road. It is in 3 parts and is completed and signed by the sender of the goods, the carrier and the person receiving the goods. If the international consignment note is used as part of the evidence, it is important that the information is complete and all the details legible. Where the overseas customer arranges for the goods to be collected ex-works the international consignment note alone is not conclusive evidence that the goods in question have left the UK. Read paragraph 6.6 for additional evidence required when making an indirect export.

    Where goods leave through a port using the Goods Vehicle Movement Service, you should retain the Goods Movement Reference of the vehicle for that journey. 

Failure to produce the appropriate and accurate evidence will result in output tax being due on the relevant goods. 

VAT: Composite or separate supplies – The A & D McFarlane case

By   10 March 2026

Latest from the courts

Yet more on composite or separate supplies. As a background to the issue please see previous relevant cases here here here and here. This is the latest the seemingly endless and conflicting series of cases on whether certain supplies are multiple or single. 

In the First-Tier Tribunal case (FTT) of Alan and Diane McFarland the appellants operated a ‘bed and breakfast’ for other people’s cattle.

The issue

The VAT issue was whether there were separate supplies:

  • zero-rated supply of animal food
  • exempt supply of land.

Additionally, the appellant contended that the supply of animal food was a principal supply, and everything else, including the land, was ancillary. 

HMRC took the view that there was a single taxable supply of ‘animal care’ and not separate supplies of exempt stabling and zero-rated feed. It also rejected the claim that the appellant had an exclusive right of occupation over any defined area, noting that there was no agreement conferring such a right with the consequence that this could not be an exempt supply. On the zero-rated animal foodstuffs point; HMRC concluded that the supplies do not qualify for zero-rating as the food provided formed part of the overall service of animal husbandry.

Legislation

  • Exemption: right over land or any licence to occupy land – The VAT Act 1994, Schedule 9, Group 1,  item 1
  • Zero-rating: animal feeding stuffs – The VAT Act 1994, Schedule 8, Group 1, Item 2.

Decision

The FTT found that there was a single standard rated supply of ‘looking after’ cattle. The supply made by the appellant fell squarely within the Levob (Levob Verzekeringen BV [C-41/04]) category, being so closely linked that they form, objectively, a single, indivisible economic supply, which it would be artificial to split. – HMRC notes on Levob here.

The supply was a fully integrated package of services directed towards the rearing and finishing of cattle. This included: daily mixing and provision of feed, management of water and housing, maintenance of handling facilities, statutory record‑keeping, and disease‑control obligations. These activities were inseparable in practice and indispensable for the operation of the recipient’s cattle‑finishing business. Neither the accommodation nor the feed, nor any other individual component, was offered or taken independently. There was a single price for the complete service. There was also a single invoice and a single description of the supply on the invoice. There was no indication on the invoice that both exempt and zero-rated services were being supplied.

The appellant provided a single composite service of animal rearing and management, to which all elements, including accommodation and feed, were merely constituent elements.

The Tribunal also dismissed the alternative argument of the that the supply of food was the principal supply, with all other elements, including accommodation and the wider activities being merely ancillary. The provision of food was not an aim in itself. The food could not sensibly be separated from the accommodation, handling, record-keeping and welfare-related functions that were also performed. It was, therefore, not the principal supply but an integrated component of the single composite supply.

The appeal was consequently dismissed.

Commentary

Yet another case on the perennial composite/single supply issue. This case was relatively straightforward and the outcome was no surprise. It is essential that businesses that potentially deal with agent/principal matters or make supplies at different VAT rates consider their position. Contracts, other documentation and the commercial reality need to be considered. We recommend that in such circumstances a review is carried out specifically to establish the correct VAT position .