
Tag Archives: penalties

VAT: Extent of zero rating for a construction by a charity

By   9 October 2017

Latest from the courts

In the First Tier Tribunal (FTT) case of The Trustees of Litton & Thorner Community Hall the issue was whether certain construction works were a completion of an initial build or whether they were an extension or an annex to a pre-existing building. And if an annex, whether it was capable of functioning independently from the existing building and whether there is a main access to the annex.

Background

The appellant began construction of a hall in 2008. It was intended that the hall would be available for a school to use and also for it to be available at for village use and other activities, such as by local youth clubs and a scout group. There was no dispute that the original construction was zero rated via VAT Act 1994, Schedule 8, Group 5, item 2  (The supply in the course of the construction of a building designed for a relevant charitable purpose).

A decision was made to install ground source heat pumps to feed the heating system. However the space occupied to accommodate the system meant that there was insufficient storage space in the hall. So at the time of construction, but before planning permission was obtained, it was decided with the builder that a steel joist should be incorporated within the east wall of the hall in order to facilitate the necessary support and access when the envisaged storage facility was added.  The additional planning permission was granted in November 2011, three years after building work commenced. The facility was eventually able to be used when work was completed in 2014. The delay was caused (not surprisingly) by funding issues. It was the VAT treatment of work relating to the addition of the storage area which was the subject of the appeal, with HMRC considering that it was either standard rated work to the building or was a standard rated extension to it.

Technical background

The provisions relevant to the appeal are VAT Act 1994, Schedule 8, Group 5, Notes 16 and 17. It is worthwhile taking a moment to consider these in their entirety:

Note 16

For the purpose of this Group, the construction of a building does not include

(a ) the conversion, reconstruction or alteration of an existing building; or

(b) any enlargement of, or extension to, an existing building except to the extent the enlargement or extension creates an additional dwelling or dwellings; or

(c) subject to Note (17) below, the construction of an annexe to an existing building.

Note 17

Note 16(c) above shall not apply where the whole or a part of an annexe is intended for use solely for a relevant charitable purpose and;

(a) the annexe is capable of functioning independently from the existing building; and

(b) the only access or where there is more than one means of access, the main access to:

(i) the annexe is not via the existing building; and

(ii) the existing building is not via the annexe.

The Appeal

The Trustees appealed on two separate and distinct bases:

(1) That the additional building was the completion of the original building and neither an extension nor an annex to it. It was their case that the temporal disconnect between the two building processes must be seen in the factual context, with particular reference to the decision to put in a lintel to allow the building to be completed when additional monies and planning permission were available. Additionally, alongside this fact was that the appellant was a non-commercial organisation and so things could not progress as expeditiously as they might have done if those things were being undertaken by a commercial organisation.

(2) The second basis is that, in any event, the additional building is zero rated by reference to paragraphs 16(c) and 17 of Group 5 to Schedule 8. It was the appellant’s case that the additional building is an annex intended for use solely for relevant charitable purposes and it meets the conditions set out in paragraph 17(a) & (b).

Decision

The FTT decided that the work was subject to zero rating. Not only was it part of the original construction (albeit that there was a significant time period between the building original work and the work on the storage area) but also, even if the storage area is considered as being separate, it was ruled that, on the facts, it was an annex rather than an extension, so it also qualified for zero rating on this basis.

Commentary

The date a building is “completed” is often an issue which creates significant disputes with HMRC, not only for charities, but for “regular” housebuilders. I have also encountered the distinction between an annex and an extension representing a very real topic, especially with academy schools. Even small changes in circumstances can create differing VAT outcomes. My advice is to seek assistance form a VAT consultant at the earliest stage possible. It may be that with a slight amendment to plans, zero rating may be obtained in order to avoid an extra 20% on building costs which charities, more often than not, are unable to reclaim.

Links to what we can offer to schools here, and charities here

Additionally, our offering to the construction industry here
VAT: Separate or composite supply? The Ice Rink Company Ltd case

By   4 October 2017

Latest from the courts – Appellant on thin ice?

In the first Tier Tribunal case of The Ice Rink Company Ltd the issue was whether supplies of admission to ice skating rink and the hire of children’s ice skates – where sold as a package were single or multiple supplies. This is yet another separate/composite/compound supply case.

As a background to the issue please see previous relevant cases here here and here (in fact, this case was referred to in this hearing).

The issue of what is a single supply and what must be split as separate supplies seems to be neverending and HMRC appears to have an appetite to challenge every moot position through the courts.

Background

As anyone who has been ice skating will be aware (I tend to avoid the places not least as a result of not wishing to demonstrate my total lack of balance or skill) you can take your own skates, or hire skates for that session. In this case, the costs were £8 to use the rink or £10 with skate hire. The sole issue in the appeal was whether, when the appellants sold a “package deal” at £10 allowing a child to skate and to hire skates, it made a single supply or two separate supplies. If they made separate supplies, the £2 hire of skates to children is zero-rated. If it is a single supply the whole package is standard rated.

Decision

The judge decided that there were two separate supplies and that the skate hire supply could be treated as zero rated. This decision was based on a number of factors put forward by the appellant and which may be summarised as:

  • Skating with skate hire is a mixed supply, as the supply of skates is distinct and separate from the supply of admission
  • Around half the customers wishing to skate brought their own skates and some customers hired skates without paying to skate (at club sessions when a club had hired the rink and they needed skates for their club members). The hire of skates was therefore capable of being carved out from a single supply
  • A single “package” price is not determinative – in this case is it clear to the customer that they have freedom of choice and the components are available separately
  • Despite what HMRC said, it is clear that the skate hire is additional and optional
  • Neither supply is predominant and neither ancillary (as HMRC have previously accepted)
  • There was physical separation between the admission booth and the skate hire zone

The decision helpful included the following observations: “In our view… it is plain that in this case there are two supplies, a supply of the use of a skating rink and the supply of hire of ice skates. Neither is ancillary to the other as they both can be, and are, purchased on their own. Far from it being artificial to split the package into two, that is precisely what is in effect done in a substantial percentage of the appellant’s transactions with those using its facilities.” And “From the customers’ viewpoint a consumer of the package is getting the two things they want. The two elements are dissociable, not because of any spatial separation between the ticket office and the skate hire booth, but because that is the only appropriate way of looking at the supply of the elements.” And “…a substantial percentage of customers will choose to buy one or other of the element but not both, and that it is possible that the same customer may at one time buy a package and at another buy only one of the elements. Therefore it makes no sense to say that the elements are not dissociable when on a majority of the occasions that users enter the reception to use the rinks they choose only one of the two main elements, entry to the rink.”

 Commentary

A sensible decision based on the facts. There does not seem to be an end to these types of cases as the decision is always based on the unique facts of each situation. It is difficult, if not impossible, to draft legislation which covers every type of scenario. Consequently, case law is very important in this area and the lead cases of CPP and Levob are the most cited. This case further illustrates that HMRC are not always correct in reaching a conclusion on multiple/composite supply cases and there is usually value in challenging their determinations. I would also say, from experience, that a review of a business’ activities can often identify such contentious areas and as always, getting it wrong can either result in an assessment and penalties, or mean that a business is paying too much VAT – not something that sits easily with me!

VAT: Latest from the courts – partial exemption attribution

By   4 October 2017

In court about courts…

In the First Tier tribunal (FTT) case of The Queen’s Club Limited the issue was whether certain input tax was attributable to the company’s taxable activities or, as HMRC contended; to both its taxable and exempt income (so that it was residual). If HMRC were correct an element of the input tax would fall to be irrecoverable via the appellants’ partial exemption calculation. A brief guide to partial exemption here 

Background

The Queen’s Club (The Club) is a well-known members’ tennis club in West London. The Club’s tennis facilities are world-class and each year the Lawn Tennis Association hires the Club’s courts to put on the Aegon Championship which is a precursor to the Wimbledon tournament and attracts many of the world’s leading players. It makes exempt supplies of sporting services to its members and also makes taxable supplies of food and drink in its bars and restaurants. It incurred VAT on the costs of refurbishing the bars, restaurant and café facilities on its premises. The Club considers that it is entitled to a full credit for input tax on those expenses as they were wholly attributable to the taxable supply of catering.

The Club’s revenue comes primarily from the membership fees that it charges. For the year 2012-13 the annual membership fee was £1820. By becoming a member of the Club, a person obtains the right to use both its sporting and non-sporting (catering) facilities. It was decided by the FTT that the Club had a discretion, but not an obligation, to provide the café etc to its members, however it was accepted that most members do not use the social facilities.  It was agreed that the membership fee was consideration for an exempt supply of services closely linked with sport for the purposes of Value Added Tax Act 1994, Schedule 9, item 10. The Club also receives five main sources of taxable income:

  • Fees from the LTA to use its courts for the Aegon Championship
  • Sales of food and drink from restaurant and bars
  • Sales of sporting and other goods
  • Provision of the use of the restaurant and bars, usually with catering
  • Rental income for certain other rooms

The decision

There was no dispute that there was a direct and immediate link between the refurbishment of the restaurant and bars and taxable supplies made from them. The question that divided the parties was whether there was also a direct and immediate link between the refurbishment the exempt membership supplies.

The judge decided that “In short, viewed objectively, what members obtain when they join the Club is a right of access to world-class sporting facilities together with such additional facilities as the Club decides, in its discretion, to offer. The focus is on the sporting facilities…” and that, viewed objectively, the renovated bars and restaurant are a means by which members are able enjoy the Club’s sporting offering. The overall conclusion was that there was no direct and immediate link between the renovation goods and services and exempt supplies that the Club made.

The decision was that the Club was entitled to credit for the full amount of input tax that it incurred.

Commentary

This case demonstrates that care is always required when costs are attributed to a business’ activities. This is especially important when the costs are significant; particularly when they are incurred on land and property. There tends to be a lot of “debate” with HMRC on such matters and slight nuances can affect attribution. These type of costs are often covered by the Capital Goods Scheme, so care must be taken over a ten year period which adds to the complexity.  As always, when considering land and property transactions it pays to obtain professional advice as mistakes are costly. A brief guide to land and property issues here

VAT due on property search fees? Whether they are disbursements

By   25 September 2017

Latest from the courts – Brabners LLP

In the First Tier Tribunal case of Brabners LLP (Brabners) the issue was whether an external search agency used by the appellant correctly treated its supplies as VAT free, and if this was the case, whether the VAT free treatment continued to the appellant’s clients by way of a disbursement.

This is an interesting case and may create historic difficulties for conveyancing solicitors.

Background

Brabners is a law firm with a real estate department. It offers conveyancing services, both to buyers and sellers, in relation to proposed property transactions, for both commercial and residential property. In order to fulfil certain legal requirements, it used an external third party entity to obtain online property searches. The Appellant stated that it uses the online system for the majority of its searches (as opposed to a postal search carried out by employees of a Local authority, or a personal search at the Local Authority’s premises). The online search is not carried out by the Appellant, but rather, a specialist online search agency (‘Searchflow’) engaged by Brabners. Searchflow obtained the required property searches from the Local Authority’s digitised or dematerialised files and registers, and passed those results back to Brabners.

Searchflow invoiced the appellant for the cost of obtaining access to documents without the addition of VAT. Brabners treated this as a disbursement and invoiced its clients for the same amount without VAT.

The issues were:

  • Should the supply by the search agency be subject to output tax?
  • Was there a single or multiple supply?
  • Whether the charge to the end user of the services should be treated as a disbursement in respect of the search element
  • Which party consumed Searchflow’s services? (Brabners, or Brabners’ clients)

Note: the disbursement position is only (practically) relevant in this case if it was decided that the search fee was VAT free. Local Authorities now (from March 2017) charge VAT for searches, so the impact is only likely to impact on past situations.

Contentions 

The main thrust of the Brabners’ argument is that the firm was requested, or expressly authorised, to obtain a search on the client’s behalf. Consequently, this meant that the firm was simply acting as the client’s agent, and the report belongs to the client. Brabners, argued that the search fees qualified as a disbursement for the purposes of VAT, and were not part of the otherwise taxable supply. It also argued that this separate treatment is intelligible and sensible. HMRC formed the view that the relevant payments cannot be treated as a disbursement as all the tests to do so were not met.  For a guide to disbursements and the relevant tests please see here

Decision

The judge decided that the relevant expenses paid to Searchflow had been incurred by the appellant “in the course of making its own supply of services to” (its client) “and as part of the whole of the services rendered by it to” (its client). Therefore Brabners had consumed the service such that it could not be a disbursement. This point in this case proves academic as it was also, unsurprisingly, decided that Searchflow’s services were standard rated, so even if it were a disbursement, the VAT would still be payable by the appellant’s client.

 Consequences

All firms which carry out conveyancing should review the VAT treatment of searches. If they have erroneously treated similar transactions as disbursements in the past, this is likely to require correction. Clearly, HMRC will be alive to this decision and it is anticipated that legal firms will be the subject of close inspection.

This case may also mean that third party search entities may be issuing retrospective VAT invoices or work which was previously treated as VAT free. This needs to be recognised and arrangements in place to recover any input tax incurred.

We are able to assist conveyancing firms with a review of the VAT position in light of this case.

VAT: Output tax on credits? A Tax point case

By   18 September 2017

Latest from the courts

In the Scottish Court of Session case of Findmypast Limited the issue was whether the sale of credits represented a taxable supply, the tax point of which was when payment was received.

Background

Findmypast carries on a business of providing access to genealogical and ancestry websites which it owns or for which it holds a licence. If a customer wishes to view or download most of the records on the website, they will be required to make a payment. This may be done by taking out a subscription for a fixed period, which confers unlimited use of the records during that period. Alternatively, the customer may use a system known as Pay As You Go. This involves the payment of a lump sum in return for which the customer receives a number of “credits”. The credits may be used to view records on the website, and each time a record is viewed some of the credits are used up. The credits are only valid for a fixed period, but unused credits may be revived if the customer purchases further credits within two years; otherwise they are irrevocably lost.

Technical

Findmypast accounted for output tax on the price of the credits at the time when they were sold.  As a consequence, VAT was paid, not only on credits which were used, but also on credits that were not redeemed (The tax point therefore similar to the current rules on the sale of single use face value vouchers. Rules here).

The taxpayer claimed repayment of the VAT accounted for on the sale of unredeemed vouchers during a period which ran up to May 2012 when the legislation was changed.

The question was whether output tax should have been accounted for at the time when the vouchers were sold or at the time the vouchers were redeemed. If the tax point was the date of redemption, then the claim would be valid. The court identified the following issues:

  • What is the nature of the supply made by the taxpayer to customers?
    • Was it was the supply of genealogical records selected by the customer and viewed or downloaded by them?
    • Or was the supply a package of rights and services, which conferred a right to search the records and download and print items from the taxpayer’s websites?

If the former is accurate, the supply only takes place if and when a particular record is viewed or downloaded.  If the latter, the supply includes a general right to search which is exercisable as soon as the credits are purchased, with the result that the supply takes place at that point.

A subtle distinction, but one which has an obviously big VAT impact.

Decision

The Court decided that where credits were not redeemed, the taxpayer is entitled to be repaid the output tax previously declared as no tax point was created. In the Court’s view, Findmypast was making the relevant documents available in return for payments received. HMRC’s contention that there was a complex, multiple supply of the facility to find and access genealogical documents such that payment created a tax point was dismissed. The court further found that the relevant payments did not qualify as prepayments (deposits) because it was not known at the time of purchase whether the credits would be redeemed (many were not) or indeed at what time they would be redeemed if they were.  It was also decided that the credits were not Face Value Vouchers per VAT Act 1994, Schedule 10A, paragraph 1(1) as they are rather mere credits that permit the customer to view and download particular documents on the taxpayer’s website, through the operation of the taxpayer’s accounting system.  And that they are not purchased for their own sake but as a means to view or download documents.

Commentary

Readers of my past articles will have identified that multiple/single supplies and tax points create have been hot topics recently, and this is the latest chapter in the story.

This case highlights that any payments received by a business must be analysed closely and the actual nature of them determined according to the legislation and case law. Not all payments received create a tax point and

Some will not represent consideration such that output tax is due. Careful consideration of the tax point rules is necessary.  Not only can the correct application of the rules aid cashflow, but in certain circumstances (such as set out in this case) it is possible to avoid paying VAT on receipts at all.

VAT – Do as HMRC say…. and if you do… they may still penalise you!

By   13 September 2017

Can you rely on a VAT ruling received from HMRC when they have been provided with full information in writing?

You would like to think so wouldn’t you? And in the past, you have been able to.

However, the long standing protection from assessments for deemed underdeclared VAT as a result of incorrect advice or actions by HMRC has been withdrawn. This was commonly known as “Sheldon Statement” protection. HMRC now state that there are some circumstances in which their primary duty is to collect tax according to the statute and it may mean that they can no longer be bound by advice they have given.  Despite all the publicity of their National Help Line and Advice Centre, plus the clearance procedures introduced to assist taxpayers with their obligations, HMRC can still renege on their advice! Even if you are fortunate enough to actually get a decision from HMRC (which is increasingly difficult and frustrating) you can’t necessarily rely on it. This is the case even if you have provided full information in writing (as required) and made a comprehensive disclosure of your position.

This makes it even more important to avoid errors and the increased risk of VAT penalties and interest. Details of the penalty regime here

This leaves the question as to whom businesses can rely on for accurate, cost effective VAT saving advice and guidance on getting VAT right?  The answer, clearly, is to contact their friendly local VAT consultant…

The Default Surcharge for late VAT payments

By   5 September 2017

A Default Surcharge is a civil penalty issued by HMRC to “encourage” businesses to submit their VAT returns and pay the tax due on time.

VAT registered businesses are required by law to submit their return and make the relevant payment of the VAT by the due date.

A default occurs if HMRC has not received your return and all the VAT due by the due date. The relevant date is the date that cleared funds reach HMRC’s bank account. If the due date is not a working day, payment must be received on the last preceding working day.

Payments on Account (POA)

If a business is required to make POA it must pay them and the balance due with the VAT Return by electronic transfer direct to HMRC’s bank account. The due dates for POA are the last working day of the second and third month of every quarterly accounting period. The due date for the balancing payment is the date shown on the business’ VAT Return. It is important to ensure that payments are cleared to HMRC’s bank by these dates or there will be a default.

Consequence of default

A business will receive a warning after the first default ‐ the Surcharge Liability Notice (SLN). Do not ignore this notice. If you fail to pay the VAT due on the due date within the next five quarters, the surcharge will be 2% of the outstanding tax. The surcharge increases to 5% for the next default, and then by 5% increments to a maximum of 15%.  Each default, whether it is late submission of the return or late payment, extends the surcharge liability period, but only late payment incurs a surcharge.

If you can’t pay the VAT you owe by the due date or are having difficulties, contact the Business Payment Support Service immediately.

Special arrangements for small businesses

There are special arrangements if a business’ taxable turnover is £150,000 or less to help if there are short term difficulties paying VAT on time. HMRC send a letter offering help and support rather than a Surcharge Liability Notice the first time there is a default. This aims to assist with any short-term difficulties before a business formally enters the Default Surcharge system. If the business defaults again within the following 12 months a Surcharge Liability Notice will be issued.

Minimum surcharges

There is a minimum of £30 for surcharges calculated at the 10% or 15% rates. There will not be a surcharge at the 2% and 5% rates if it is calculated it to be less than £400. However, a Surcharge Liability Notice Extension extending the surcharge period will be issued and the rate of surcharge if you default again within the surcharge period will be increased.

Circumstances when HMRC will not levy a surcharge

There’s no liability to surcharge if a business:

  • submits a nil or repayment return late
  • pays the VAT due on time but submit your return late

HMRC will not issue a surcharge in these circumstances because there is no late payment involved. If a business had defaulted previously HMRC will issue a Surcharge Liability Notice Extension extending the surcharge period because the return is late, but they will not increase the rate of surcharge.

Time limit

A business’ liability to surcharge will expire if a business submits all of its returns and payments for tax periods ending on or before the end of the surcharge liability period on time.

Reasonable excuse

If a business has a reasonable excuse for failing to pay on time, and it remedies this failure without unreasonable delay after the excuse ends, it will not be liable to a surcharge.

There’s no statutory definition of reasonable excuse and it will depend on the particular circumstances of a case. A reasonable excuse is something that prevented the business meeting a tax obligation on time which it took reasonable care to meet. The decision on whether a reasonable excuse exists depends upon the particular circumstances in which the failure occurred. There is a great deal of case law on this particular issue. Please contact us should there be doubt about a reasonable excuse.

Disagreement over a surcharge

If you disagree with a decision that you are liable to surcharge or how the amount of surcharge has been calculated, it is possible to:

  • ask HMRC to review your case
  • have your case heard by the Tax Tribunal

If you ask for a review of a case, a business will be required to write to HMRC within 30 days of the date the Surcharge Liability Notice Extension was sent. The letter should give the reasons why you disagree with the decision.

Examples when a review may be appropriate are if a business considers that:

  • it has a reasonable excuse for the default
  • HMRC applied the wrong rate of surcharge
  • HMRC used the wrong amount of VAT when calculating the surcharge
  • there are exceptional circumstances which mean the default should be removed

A business will still be able to appeal to the Tribunal if it disagrees with the outcome of the HMRC review.

We are very experienced in dealing with disputes over Default Surcharges, so if you feel that one has been applied unfairly, or wish to explore your rights, please let us know.

VAT Public Notice 700 Updated

By   25 August 2017

Notice 700: The VAT Guide has been updated.

This HMRC Notice is a “starting point” for general VAT information and provides a guide to all the main VAT rules and procedures. It also provides assistance with the problems faced by business and includes an index which helps users find further information by referring to a particular section or paragraph in one of HMRC’s other, more specialised publications. There have been over 30 changes to the Notice which was last updated in 2016.

A full list of changes is set out in the Notice, but the most salient are as follows:

  • Additional guidance on MOSS – para 4.8.4
  • Single and mixed supplies – para 8.1
  • Continuous supplies to connected persons – para 14.3.1
  • Various commentary on invoices (including electronic invoicing) – paras 16.6, 16.8, 17.7 17.8
  • Accounting schemes – para 19.2
  • Agents registered for VAT acting in their own name when the customer is not registered – para 1.2
  • Penalties for inaccuracies – para 27.3
  • Integrity of supply chains – para 27.5.2

The number of changes in just one year highlights the fast pace of the tax and the number of challenges which taxpayers have won. I cannot see this pace letting up in the future either.

As always, if you have any queries about the changes, please contact us.

VAT – Business Entertainment Flowchart. What input tax may I recover?

By   26 June 2017

VAT – Recovery of input tax incurred on entertainment

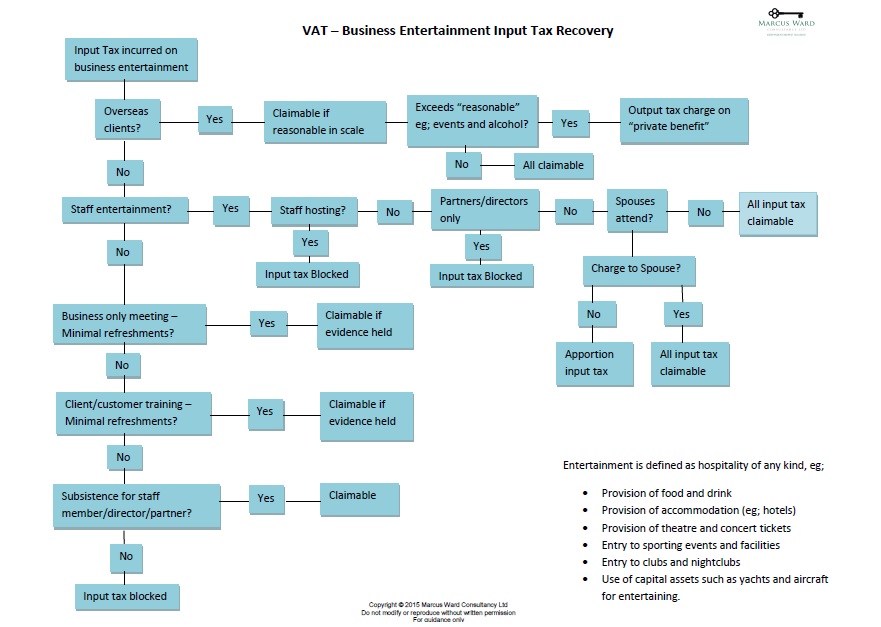
One of the most common questions asked on “day-to-day” VAT is whether input tax incurred on entertainment is claimable.  The answer to this seemingly straightforward question has become increasingly complex as a result of; HMRC policy, EC involvement and case law.

Different rules apply to entertaining; clients, contacts, staff, partners and directors depending on the circumstances.  It seems reasonable to treat entertaining costs as a valid business expense.  After all, a business, amongst other things, aims to increase sales and reduce costs as a result of these meetings.  However, HMRC sees things differently and there is a general block on business entertainment.  It seems like HMRC does not like watching people enjoying themselves at the government’s expense!

If, like me, you think in pictures, then a flowchart may be useful for deciding whether to claim entertainment VAT.  It covers all scenarios, but if you have a unique set of circumstances or require assistance with some of the definitions, please contact me.

We have recently carried out a series of presentations, which, amongst other subjects, covered business entertainment. Should you require VAT training or presentations, don’t forget our comprehensive service here which can be tailored to your needs.

VAT -Business Entertainment Flowchart

Business Entertainment flow chart

Download here: VAT Business Entertainment Input tax recovery flowchart

VAT treatment of deposits and advance payments

By   5 June 2017

One query that constantly reappears is that of the VAT treatment of deposits.

This may be because there are different types of deposits with different VAT rules for each. I thought that it would be helpful for all the rules to be set out in one place, and some comments on how certain transactions are structured, so…

Broadly, we are looking at the tax point rules. The tax point is the time at which output tax is due and input tax recoverable. More on tax points here 

A business may have various commercial arrangements for payments such as:

  • receiving advance payments
  • being paid in instalments
  • credit sales
  • periodic payments for continuous supplies
  • security deposits for goods hired

I consider these below, as well as some specific arrangements:

Advance payments and deposits

An advance payment, or deposit, is a proportion of the total selling price that a customer pays a business before it supplies them with goods or services.

The tax point if an advance payment is made is whichever of the following happens first:

  • the date a VAT invoice for the advance payment is issued
  • the date you the advance payment is received

The VAT due on the value of the advance payment (only, not the full value of the overall supply) is included on the VAT return for the period when the tax point occurs.

If the customer pays the remaining balance before the goods are delivered or the services are performed, a further tax point is created when whichever of the following happens first:

  • the date a VAT invoice for the balance is issued
  • payment of the balance is received

So VAT is due on the balance on the return for when the further tax point occurs.

Returnable deposits

A business may ask its customers to pay a deposit when they hire goods. No VAT is due if the deposit is either:

  • refunded in full to the customer when they return the goods safely
  • kept by you to compensate you for loss or damage

Forfeit deposits

If a customer is asked for a deposit against goods or services but they then don’t buy them or use the services, it may be decided to retain the deposit. Usually the arrangement is that the customer is told/agrees in advance and it is part of the conditions for the sale. This arrangement is known as forfeit deposit. It often occurs when, for example, an hotel business makes a charge for reserving a room.

VAT should be declared on receipt of the deposit or when a VAT invoice is issued, whichever happens first.

If the deposit is retained (because the customer changes their mind about the goods or service and doesn’t want them any more) there is no VAT due as no supply has been made. If output tax has already been declared, the business needs to adjust for the amount of the retained deposit on the next VAT return. If the sale goes ahead, the rules for advance payments above applies.

Continuous supplies

If you supply services on a continuous basis and you receive regular or occasional payments, a tax point is created every time a VAT invoice is issued or a payment received, whichever happens first. An article on tax planning for continuous supplies here

If payments are due regularly a business may issue a VAT invoice at the beginning of any period of up to a year for all the payments due in that period (as long as there’s more than one payment due). If it is decided to issue an invoice at the start of a period, no VAT is declared on any payment until either the date the payment is due or the date it is received, whichever happens first.

Credit and conditional sales

This is where the rules can get rather more complex.

  • A credit sale means the sale of goods which immediately become the property of the customer but where the price is paid in instalments.
  • A conditional sale is where goods are supplied to a customer but the goods remain the seller’s property until they are paid for in full.

The tax point for a credit sale or a conditional sale is created at the time you supply the goods or services to your customer. This is the basic tax point and is when you should account for the VAT on the full value of the goods.

This basic tax point may be over-ridden and an actual tax point created if a business:

  • issues a VAT invoice or receives payment before supplying the goods or services
  • issues a VAT invoice up to 14 days after the basic tax point

Credit sales where finance is provided to the customer

If goods are offered on credit to a customer and a finance company is not involved, the supplier is financing the credit itself. If the credit charge is shown separately on an invoice issued to the customer, it will be exempt from VAT. Other fees relating to the credit charge such as; administration, documentation or acceptance fees will also be exempt. VAT is declared on the full value of the goods that have been supplied on the VAT Return for that period.

If goods or services are supplied on interest free credit by arranging with a customer for them to pay over a set period without charging them interest then VAT is declared on the full selling price when you make the supplies.

Credit sales involving a finance company

When a business makes credit sales involving a finance company, the finance company either:

  • becomes the owner of the goods, eg; when a purchase is financed by a hire-purchase agreement
  • does not become the owner of the goods, eg; when a purchase is financed by a loan agreement

Hire purchase agreements

If the finance company becomes the owner of goods, the business is supplying the goods to the finance company and not the customer. There is no charge for providing the credit, so the seller accounts for VAT on the value of the goods at the time they are supplied to the finance company. Any commission received from the finance company for introducing them to the customer is usually subject to VAT.

Loan agreements

If the finance company does not become owner of the goods, the supplier is selling the goods directly to its customer. The business is not supplying the goods to the finance company, even though the finance company may pay the seller direct.  VAT is due on the selling price to the customer, even if the seller receives a lower amount from the finance company. The contract between the customer and the finance company for credit is a completely separate transaction to the sale of the goods.

Specific areas 

The following are areas where the rules on the treatment may differ

Cash Accounting Scheme

If a business uses the cash accounting scheme here it accounts for output tax when it receives payment from its customers unless it is a returnable deposit

Property

Care should be taken with deposits in property transactions.  This is especially important if property is purchased at auction.

These comments only apply to the purchase of property on which VAT is due (commercial property less than three years old or subject to the option to tax).  If a deposit is paid into a stakeholder, solicitor’s or escrow account (usually on exchange) and the vendor has no access to this money before completion no tax point is created. Otherwise, any advance payment is treated as above and creates a tax point on which output tax is due to the extent of the deposit amount. Vendors at auction can fall foul of these rules. If no other tax point has been created, output tax is due on completion.

Tour Operators’ Margin Scheme (TOMS)

TOMS has distinct rules on deposits.  Under normal VAT rules, the tax point is usually when an invoice is issued or payment received (as above).  Under TOMS, the normal time of supply is the departure date of the holiday or the first occupation of accommodation. However, in some cases this is overridden.  If the tour operator receives more than one payment, it may have more than one tax point. Each time a payment is received exceeding 20% of the selling price, a tax point for that amount is created. A tax point is also created each time the payments received to date (and not already accounted for) exceed 20% when added together. There are options available for deposits received when operating TOMS, so specific advice should be sought.

VAT Registration

In calculating turnover for registration, deposits must be included which create a tax point in the “historic” test.  Care should also be taken that a large deposit does not trigger immediate VAT registration by virtue of the “future” test. This is; if it is foreseeable at any time that receipts in the next 30 days on their own would exceed the turnover limit, currently £85,000, then the registration date would be the beginning of that 30-day period.

Flat Rate Scheme

A business applies the appropriate flat rate percentage to the value of the deposit received (unless it is a returnable deposit).  In most cases the issue of an invoice may be ignored if the option to use a version of cash accounting in the Flat Rate Scheme is taken. More on the FRS here and here

Please contact us if you have any queries on this article or would like your treatment of deposits reviewed to:

  • Ensure treatment is correct to avoid penalties, and/or;
  • Establish whether planning is available to properly defer payments of output tax under the tax point rules.