
Category Archives: HMRC Publications

The ABC of VAT – property

By   28 May 2019

A glossary

Anyone who has had even the slightest brush with VAT will know that it is a very complex tax. Now, multiply that complexity by the intricacy and occasionally arcane nature of property law and one may see that the outcome will be less than straightforward. I have produced a general guide and an article on residential property VAT Triggerpoints

I hope the following glossary will help with steering through some of the difficulties.

  • Annex– a building which is joined to or is next to a larger main building usually an extension or addition to a building
  • Assign – to transfer the right or interest in a property from one party to another
  • Break clause – a clause allowing either landlord or tenant to give written notice after a particular date or period of the tenancy in order to end the tenancy
  • Beneficial owner – party deemed to make a supply of property rather than the legal owner
  • Blocked input tax – VAT which a developer is unable to recover when constructing a new dwelling. Typically, expenditure on good such as; carpets, fitted furniture, and gas and electrical appliances
  • Building materials– goods ordinarily incorporated into a property which attracts similar VAT treatment to the construction services.
  • Capital Goods Scheme(CGS) – a method of calculating the recovery amount of input tax incurred on property over a ten-year period, Details of the CGS here
  • Certificate – a document issued to a supplier in order to obtain certain zero-rated or reduced-rated building work
  • Change of number of dwellings– usually a conversion from commercial to residential, or a single house into flats (or flats into a single house) at 5% VAT
  • Consideration– a thing done or given in exchange for something else = a supply. Usually quantified in money, but in some cases non-monetary consideration
  • Construction of new dwellings – a zero rated supply
  • Contract – legal document detailing the agreement of terms between the vendor and buyer
  • Contractor – entity responsible for building works
  • Conversion–work on a non-residential building which results in a property designed as a dwelling(s) being created
  • Covenants – rules governing the property in its title deeds or lease. May impact the definition of dwellings
  • Curtilage– either a garden, or an area surrounding a building which is deemed to be part of the property
  • Designed as a dwelling– a property initially designed for residential use, regardless of any subsequent alternative use
  • Dilapidations – items that have been damaged during a tenancy for which the tenant is responsible for the cost of repair or replacement. Usually VAT free
  • DIY Housebuilders’ Scheme – a scheme which ‘self-builders’ to recover VAT on a new build dwelling or conversion. Details here
  • Dwelling– a building deemed to be residential
  • Empty house – if, in the ten years before work on a dwelling starts, it has not been lived in, the work may be subject to 5% rather than 20% VAT
  • Exempt– a supply that is VAT free. It usually results in attributable input tax falling to be irrecoverable
  • Facade– a wall (or two walls on a corner plot) which may be retained without affecting the zero rating of a new dwelling construction
  • Grant– a supply of an interest in land
  • Holiday home – the sale or long lease of a holiday home cannot be zero-rated even if it is designed as a dwelling
  • Housing Association – a non-profit organisation which rents residential property to people on low incomes or with particular needs
  • In the course of construction– meaningful works that have occurred in relation to the construction of a building (but prior to its completion)
  • Incorporated goods – goods sold with a new dwelling which are zero rated and to which the input tax block does not apply. See white goods
  • Input tax– VAT incurred on expenditure associated with property
  • Interest in, or right over, land– the right to access to and use of, land. Usually via ownership or lease
  • Lease – legal document governing the occupation by the tenant of a premises for a specific length of time
  • Licence to occupy– a permission to use land that does not amount to a tenancy
  • Live-work units – a property that combines a dwelling and commercial or industrial working space. Usually subject to apportionment
  • Major interest–a supply of a freehold interest or a lease exceeding 21 years
  • Multiple occupancy dwelling – a dwelling which is designed for occupation by persons not forming a single household
  • New building–a commercial building less than three years old the sale of which is mandatorily standard
  • Non-residential– a commercial building which is not used as a dwelling
  • Open market value – likely sale price with a willing seller and buyer, with a reasonable period of marketing and no special factors affecting the property
  • Option to tax (OTT) – act of changing the exempt sale or letting of a commercial into a taxable supply. The purpose is to either; recover input tax or avoid input tax being charged. Details here
  • OTT disapplication– the legal removal of a vendor’s option to tax
  • OTT not applicable – the OTT does not apply to residential buildings (so VAT can never apply to dwellings)
  • OTT revocation– the ability to revoke an option to tax after six months or twenty years
  • Partial exemption– a calculation to attribute input tax to exempt and taxable. Generally, VAT incurred in respect of exempt supplies is irrecoverable
  • Person constructing – a developer, contractor or sub-contractor who constructs a building
  • Premium – upfront payment for a supply of property
  • Relevant Charitable Purpose (RCP)–the use by a charity for non-business purposes or for use as a village hall or similar
  • Relevant Residential Purpose (RRP)– dwelling used for certain defined residential purposes, eg; children’s home, a hospice or student accommodation
  • Reverse surrender– a tenant surrenders an onerous lease to the landlord and makes a payment to surrender
  • Share of freehold – where the freehold of the property is owned by a company and the shareholders are the owners of the property
  • Single household dwelling– a building designed for occupation by a single household
  • Snagging – the correction of building faults. Usually follows the VAT liability of the original work
  • Stamp Duty Land Tax (SDLT) – tax paid by a purchaser of a property. SDLT is increased if the sale of a commercial property is the subject of an option to tax
  • Substantial reconstruction– certain significant works to a listed building
  • Surrender– a tenant surrenders the lease to the landlord in return for payment
  • Taxable supply– a supply subject to VAT at the standard, reduced or zero-rate
  • Use as a dwelling – a building which was designed or adapted for use as someone’s home and is so used
  • Vendor – entity selling a property
  • Transfer of a Going Concern (TOGC) – the VAT free sale of the assets of a business as a going concern. This may include a tenanted property
  • Zero-rated– a taxable supply subject to VAT at a rate of 0%

We strongly recommend that advice is obtained if any property transaction is being undertaken.

Details of our land and property services may be found here.
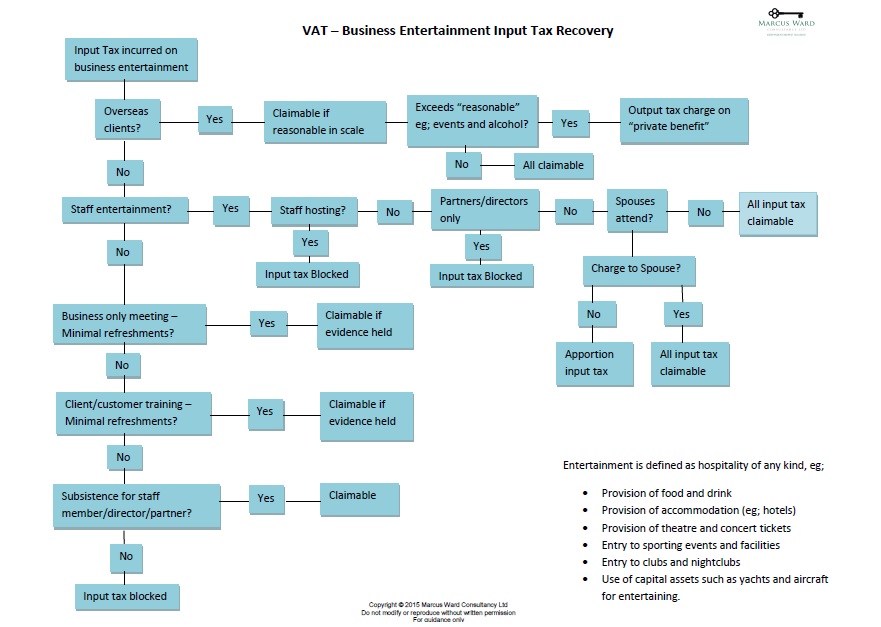
VAT – Business Entertainment Flowchart. What input tax may I recover?

By   10 May 2019

Input tax recovery on entertainment

One of the most common questions asked on “day-to-day” VAT is whether input tax incurred on entertainment is claimable.  The answer to this seemingly straightforward question has become increasingly complex as a result of; HMRC policy, EC involvement and case law.  Different rules apply to entertaining; clients, contacts, staff, partners and directors depending on the circumstances.  It seems reasonable to treat entertaining costs as a valid business expense.  After all, a business, amongst other things, aims to increase sales and reduce costs as a result of these meetings.  However, HMRC sees things differently and there is a general block on business entertainment.  It seems like HMRC does not like watching people enjoying themselves at the government’s expense!

If, like me, you think in pictures, then a flowchart may be useful for deciding whether to claim entertainment VAT.  It covers all scenarios, but if you have a unique set of circumstances or require assistance with some of the definitions, please contact me.

VAT – Business Entertainment Flowchart

Business Entertainment flow chart

The future of VAT and online marketplaces

By   7 May 2019

Latest

The Organisation for Economic Co-operation and Development (OECD) recently held a forum which considered how to level the playing field between traditional and online businesses and to collect the correct amount of tax. It is recognised that the current rules and different application of those rules in different countries has led to VAT not being collected in full in respect of online transactions.

OECD

The OECD Global Forum on VAT is a platform for a global dialogue on international VAT standards and key issues of VAT policy and operation.

The report

The subsequent report The role of digital platforms in the collection of VAT/GST on online sales focuses on the design of rules and mechanisms for the effective collection of VAT on digital sales of goods, services and intangibles, including sales by offshore digital sellers. It states that it provides “practical guidance to tax authorities on the design and implementation of a variety of solutions for enlisting the platforms economy, including e-commerce marketplaces and other digital platforms, in the effective and efficient collection of VAT/GST on digital sales”.

Background

Tax action is necessary as global B2C e-commerce sales of goods alone are now estimated to be worth in the region of USD 2 trillion annually with projections indicating they may reach USD 4.5 trillion by 2021, USD 1 trillion of which is estimated to be cross-border e-commerce with approximately 1.6 billion consumers buying online. This clearly represents considerable VAT revenue which is at stake.

See details on online evasion here

Issues

The problems which have been identified in previous report are:

  • imports of low-value parcels from online sales which are treated as VAT free in many jurisdictions, and
  • the strong growth in the trade of services and intangibles, particularly B2C, on which often no, or an inappropriately low amount of VAT is levied due to the complexity of enforcing VAT payment on such supplies

Exemptions for imports of low-value goods have become increasingly controversial in the growing digital economy. At the time when most of these exemptions were introduced, internet shopping did not exist and the level of imports benefitting from the relief was relatively small. Over recent years, many countries have seen a significant and rapid growth in the volume of low-value imports of goods on which VAT is not collected. This results in decreased VAT revenues and unfair competitive pressures on domestic retailers who are required to charge VAT on their sales.

Summary

The focus was on the rôle of digital platforms. These are capable of collecting a vast amount of data. The report stated that it is reasonable to require this information/data to be shared and that is proportionately relevant for VAT compliance purposes, ie; necessary to satisfy the tax authorities that the tax for a supply has been charged and accounted for correctly by the underlying supplier.

The two potential models are:

  • to make the digital platform fully liable for the payment and remittance of VAT on the online sales they facilitate
  • or, alternatively, to limit the responsibility of the digital platforms to simply assisting authorities in the collection of VAT

Implementation

Two options could be considered for the implementation of any information sharing obligation for digital platforms in connection to online sales:

  • provision of information on request. Under this option, a jurisdiction requires that a digital platform retains records of the sales that are subject to VAT in that jurisdiction, and that this information be made available on request.
  • systematic provision of information. Via this option, a digital platform is required to systematically and periodically provide information on online sales carried out via the platform to the tax authority of the jurisdiction of taxation.

Overall

The report is a good “solid” and long study (I cannot however, recommend it as holiday reading, although the above précis may assist). The proposed solutions are sensible, considered and workable and are likely to, at least, provide more equality and a better way for tax authorities to collect tax which is due.

Changes to recovery of VAT on imports

By   15 April 2019

HMRC have recently issued RCB 2 (2019) which sets out HMRC’s view on Toll Manufacturers (TM). TM is an arrangement in which a company which has a specialised equipment processes raw materials or semi-finished goods for another company. It may also be called toll processing. Typically, a TM will import, say, pharmaceutical goods, process and distribute them within the UK for clinical trials on behalf of an overseas owner.

HMRC has become aware that a number of UK TMs have paid import VAT on behalf of overseas customers have also claimed a corresponding deduction for input tax under VAT Act 1994 Section 24. However, there is no provision in UK law for such deduction.

Current treatment

TMs will usually act as importer and recover import VAT via a C79 despite them not being the owner of the goods (the owner instructs the TM to carry out works on their goods on their behalf).

HMRC has now confirmed that this VAT treatment is incorrect, and it will no longer be permitted.

New treatment

Only the owner of the goods will be treated as the importer and be able to recover import VAT. TMs will no longer be able to claim this VAT.

However, HMRC will not require TMs to make adjustments to past claims and the treatment will only be required going forward.

Introduction

The change comes into effect from 15 July 2019

Affect

Affected TMs are likely to need to make significant changes to their systems before that date.

Overseas owners of the relevant goods will either need to:

  • register for UK VAT and claim the import VAT on a “regular” return, or
  • make a claim via the Thirteenth VAT Directive (86/560/EEC)

NB: In cases where title has passed before import into the UK (businesses sell on the goods before importing them into the UK so ownership and title has passed to the new owner, however the business that sold the goods acts as importer on UK import declarations, pays the import VAT to HMRC and receives the import VAT certificate – C79) the correct procedure is for the new owner of the goods to be the importer of record and reclaim the import VAT and not the previous owner.

As with many areas of VAT, a No-Deal Brexit is likely to increase the complications for such cross-border transactions in the future.

Please contact us if you have any queries or require assistance on this matter.

VAT: Increased input tax recovery for suppliers of financial services – Brexit

By   5 April 2019

If the UK leaves the EU in a no-deal scenario there may be a benefit for UK based suppliers of financial and insurance services (so called Specified Supplies) to recipients in the EU. These Specified Supplies attract beneficial input VAT treatment pursuant to the VAT (Input Tax) (Specified Supplies) Order 1999 (the Specified Services Order). 

Current position

Currently, these Specified Supplies are exempt and consequently, there is no right to deduct input tax incurred in connection with such services. However, if the Specified Supplies are provided to recipients located outside the EU, they are also VAT free, although any attributable input tax is recoverable; a good VAT position.

Post Brexit position

If the UK leaves the EU, the VAT treatment of supplies to non-EU countries is also applicable to the EU 27 countries; the EU would essentially become a “third country”.

Example

A City of London based bank supplies financial services to both Germany and the US clients. Income from these two clients is 50:50. At the current time the bank would be restricted to a claim of circa half of the VAT it incurs on expenditure in the UK. After Brexit, via The Value Added Tax (Input Tax) (Specified Supplies) (EU Exit) (No. 2) Regulations 2019 all input tax incurred will be recoverable in full.

What are Specified Supplies?

Specified Supplies are broadly:

  • the issue, transfer or receipt of, or any dealing with, money, any security for money or any note or order for the payment of money.
  • granting of credit
  • dealing in; shares, stocks, bonds, notes (other than promissory notes), debentures, debenture stock
  • the operation of any current, deposit or savings account.
  • the management of certain investment funds/schemes
  • insurance
  • and intermediary services in respect of the above supplies

This list is not exhaustive and is only a very general example of types of supplies which may be considered as Specified Supplies. Please seek advice on specific services.

Other matters

The government says that this change will ensure that UK businesses compete for business in the EU on an even footing with businesses in other non-EU countries.

The proposed legislation also provides that partial exemption special methods (PESM) agreed before a no-deal Brexit will be honoured so businesses will not need to apply to HMRC for approval of a new PESM. Please see guide to partial exemption here

NB: If a deal is agreed between the UK and the EU, the above legislation will not be enacted, and the current VAT treatment will continue throughout the implementation period set out in a withdrawal agreement.

VAT: HMRC Impact Assessment of a No-Deal Brexit

By   1 April 2019

HMRC have issued an impact assessment for VAT and services if the UK leaves the EU without a deal.

The impact assessment covers the effect on businesses of amendments to existing VAT legislation and the introduction of transitional provisions for the supply of services between the UK and the EU

Summary

Under current rules:

  • VAT is charged on most goods and services sold within the UK and the EU
  • the place of supply rules for services determine the country in which a business should charge and account for VAT

If the UK leaves the EU without a deal, he UK will continue to have a VAT system. This is unsurprising as it is a major revenue raiser for the Treasury and the taxpayer is required to do all the heavy lifting the tax involves.

HMRC say the published Statutory Instruments (Sis – details of which may be found in the impact assessment but mainly The Taxation – Cross-border Trade Act 2018) broadly maintain the current VAT treatment in the event of a No-Deal Brexit. It expects that “they will have either a negligible impact on the administrative burden on businesses or no impact.”

This seems, prima facie, difficult to swallow.

HMRC also anticipate that an exception to the above is the removal of the VAT Mini One Stop Shop (MOSS), which “may have a significant ongoing cost for some EU and non-EU businesses.”

The impact assessment refers to the Economic Analysis of Brexit which makes interesting reading.

Of course, the House has voted against a No-Deal Brexit, so we can rely on that… can’t we?

VAT MOSS and No-Deal Brexit

By   11 March 2019

In the event of an increasingly likely no deal Brexit, changes have been put in place to the existing MOSS (Mini One Stop Shop) arrangements. Details of MOSS here.

These intended changes will affect UK businesses which provide electronically supplied services such as  cross-border telecommunication, television and radio broadcasting, or digital services to non-business (eg; individuals) recipients in the EU.

Such services include:

  • website hosting
  • supply of software
  • access to databases
  • downloading apps or music
  • online gaming
  • distance teaching

The existing threshold of £8818 pa introduced by Schedule 4A, para 15(1) of the VAT Act 1994 will be removed via SI2019/404.

This means that if there is a no deal Brexit UK businesses supplying such services will either be required to:

  • register for Non-Union MOSS, or
  • register for VAT in each EU Member State in which they made a sale (where the customer belongs),

MOSS Non-Union Scheme 

A business may use the Non-Union scheme when it supplies cross-border electronically supplied services to consumers in all EU countries (including the EU country selected as the Member State of identification).

The EU countries where a business supplies services to are known as Member States of consumption.

Selecting a member state of identification

A business must designate a Member State of identification. This can be any EU country a business chooses. A business may change the member state of identification at a later date if it wants. Again, this can be any EU country a business chooses.

Registration

A business registers online via the Member State of identification’s portal.

VAT rules

A business will be allocated a VAT number by the EU country chosen to be the Member State of identification and charge VAT at the rate of the EU countries where its customers reside. The same invoicing rules as your Member State of identification must be used (although an invoice is not required in most countries when supplying services under the MOSS scheme).

VAT returns

A business must submit detailed online quarterly VAT returns within 20 days of the end of each return period. The information is then securely transferred from your Member State of identification to the relevant Member State of consumption.

VAT rates

VAT rates can be checked for the supply of telecommunications, broadcasting and electronically supplied services using the Tax Information Communication database.

For further information and to register for MOSS please see here.

VAT: Input tax claims – alternative evidence

By   7 March 2019

What can be used to make a claim?

It is well known that in order to claim input tax on expenditure a business is required to have a valid tax invoice to support it. But what if there is no VAT invoice? Can HMRC accept any other evidence to support a claim? Well, the answer is yes… sometimes.

HMRC has discretion provided by EC law. The right to deduct is given by Article 167 of the Principal VAT Directive (via VAT Regulations 1995/2518 Reg 29(2) in the UK). Specifically, the wording most relevant here is “…such other documentary evidence of the charge to VAT as the Commissioners may direct.” Broadly, a business must hold the correct evidence before being able to exercise the right to deduct.

Where claims to deduct VAT are not supported by a valid VAT invoice HMRC staff are required to consider whether there is satisfactory alternative evidence of the taxable supply available to support deduction. HMRC staff should not simply refuse a claim without giving reasonable consideration to such evidence. HMRC has a duty to ensure that taxpayers pay no more tax than is properly due. However, this obligation is balanced against a duty to protect the public revenue.

Full details of tax invoices here.

 What HMRC consider

HMRC staff are required to work through the following checklist:

  • Does the business have alternative documentary evidence other than an invoice (for example a supplier statement)?
  • Does the business have evidence of receipt of a taxable supply on which VAT has been charged?
  • Does the business have evidence of payment?
  • Does the business have evidence of how the goods/services have been consumed or evidence regarding their onward supply?
  • How did the business know the supplier existed?
  • How was the business relationship with the supplier established? For example: How was contact made?
  • Does the business know where the supplier operates from (have staff visited?)
  • How did the business contact them?
  • How does the business know the supplier can supply the goods or services?
  • If goods, how does the business know they are not stolen?
  • How does the business return faulty supplies?

Outcome

If the responses to the above tests are credible, HMRC staff should exercise their discretion to allow the taxpayer to deduct the input tax. Overall, HMRC are required to be satisfied that sufficient evidence is held by the business which demonstrates that VAT has been paid on a taxable supply of goods or services received by that business and which were used by that business for its taxable activities

Challenge HMRC’s decision

A business may only challenge HMRC’s decision not to allow a claim (did not exercise its discretion) if it acted in an unfair or unreasonable way. In these cases, the onus is on the taxpayer to demonstrate that HMRC have been unreasonable in not using the available discretion. This is quite often a difficult thing to do.

Case law

Not surprisingly, there is significant case law on this subject. The most relevant and recent being the Upper Tribunal (UT) cases of James Boyce and Scandico Ltd.

Tips

If possible, always obtain a proper tax invoice from a supplier, and don’t lose it! The level of evidence required when no invoice is held usually depends on the value of the claim. There would be a difference between persuading an inspector that £20 input tax on stationery is recoverable and the claiming of £200,000 VAT on a property purchase is permissible. As always in VAT, if you get it wrong and claim VAT without the appropriate evidence there is likely to be a penalty to pay.

If you, or your clients are in dispute with HMRC on input tax claims, please contact us.

VAT: More on the Mercedes Benz Financial Services case – PCP

By   1 March 2019

Further to my article on the Mercedes Benz Financial Services (MBFS) case on Personal Contract Purchase (PCP), HMRC has published a Briefing Note – Changes to the VAT treatment of PCPs

HMRC has fully implemented the findings in the MBFS CJEU case. In summary, HMRC state that:

“The correct treatment of PCP and similar contracts depends on the level at which the final optional payment is set:

  • if, at the start of the contract, it is set at or above the anticipated market value of the goods at the time the option is to be exercised, the VAT treatment of the contract will follow the MBFS It is a supply of leasing services from the outset and VAT must be accounted for on the full value of each instalment, there is no advance, or credit, so there is no finance
  • if, at the start of the contract, it is set below the anticipated market value, such that a rational customer would buy the asset when they exercise the option, it is a supply of goods, with a separate supply of finance. VAT is due on the supply of goods in full at the outset of the contract, the finance is exempt from VAT”

This treatment must be used by 1 June 2019. Past declarations which have been in error must be adjusted per PN 700/45. Businesses affected by the changes may also need to consider adjustments to input tax claimed, or forgone in respect of partial exemption. A guide to partial exemption here.

Claiming EU VAT refunds after Brexit

By   25 February 2019

HMRC has confirmed that in the event of a No Deal Brexit businesses belonging in the UK will no longer be able to make claims for VAT incurred in other EU Member States using the electronic refund system.

Businesses claiming via the EU VAT refund electronic system need to submit a refund claim for 2018 by 5pm on 29 March 2019. If claims are submitted after that date HMRC will be unable to send the claim to the relevant EU Member State.

If a business incurs VAT in an EU Member State in 2019 it should not use the EU VAT refund system to make a claim as it is likely to be rejected by that Member State.

After 29 March, a business must claim VAT refunds from EU Member States directly by using the existing process for businesses based outside the EU (similar to the previous EC Eighth Directive claims for those with a good memory and in line with current the EC Thirteenth Directive). This includes outstanding claims that relate to 2018 expenses, and claims relating to 2019.

It is important to understand the process for each EU Member State as it can vary. For example:

  • the deadline for making your claim may be different
  • you may need to supply a certificate of Taxable Status to support a claim
  • you may need to appoint a tax representative in the EU Member State of refund

Check the EU’s Europa website for country specific information on VAT.

This is yet another reason (should one be needed) that a No Deal Brexit will create significant burdens on businesses. It will mean that up to 27 separate claims, in the language of the Member State in which the claim is made, rather than a single application. Good luck everybody!