Tag Archives: vat-planning

VAT e-audits: A warning

By   15 October 2015

The increase in the sophistication and use of data analysis software has enabled HMRC and tax authorities worldwide to increase the number of indirect tax VAT e-audits.

This has led to an increase in, and higher quantum of; assessments, penalties and interest.  The use of more automated resources means that HMRC is capable of auditing a greater amount of information from a greater number of businesses.

Even greater care must be taken now with recording and reporting transactions and the application of calculations such as partial exemption.  The need for accurate and timely records has never been more important. It’s crucial that the basics of compliance are taken care of, as well as seeking advice and reviews on specific issues.

These issues are summarised here

Please contact us if you feel that your VAT systems need to be checked, or if you have any doubts about the accuracy of your business’ indirect tax reporting.

We offer a full range of reviews, from a straightforward healthcheck to a full report on a business.

As the severe motto has it:  Comply or die!

VAT Land and Property – Why Opt To Tax?

By   5 October 2015

Opting to tax provides a unique situation in the VAT world. It is the sole example of where a supplier can choose to add VAT to a supply….. or not.

VAT free supplies

The sale or letting of a property is, in most cases, exempt by default. However it is possible to apply the option to tax (OTT) to commercial property. This has the result of turning an exempt supply into a taxable supply at the standard rate.  (It is not possible to OTT a residential property).

Why opt?

Why would a supplier then deliberately choose to add VAT on a supply?

The only purpose of OTT is to enable the optor to recover or avoid input tax incurred in relation to the relevant land or property. The OTT is a decision solely for the property owner or landlord and the purchaser or tenant is not able to affect the OTT unless specific clauses are included in the lease or purchase contracts. Care should be taken to ensure that existing contracts permit the OTT to be taken.  Despite a lot of misleading commentary and confusion, it is worth bearing in mind that the recovery or avoidance of input tax is the sole reason to OTT.

Once made the OTT is usually irrevocable for a 20 year period (although there are circumstances where it may be revisited within six months of it being taken).  There are specific rules for circumstances where the optor has previously made exempt supplies of the relevant land or property. In these cases H M Revenue & Customs’ (HMRC) permission must usually be obtained before the option can be made.

Two part process

The OTT is a two part process.

  • The first part is a decision of the business to take the OTT and it is prudent to minute this in Board meeting minutes or similar. Once the decision to OTT is taken VAT may be added to a sale price or rent and a valid tax invoice must be raised.
  • The second part is to formally notify HMRC (after obtaining permission if necessary).  The form on which this is done is a VAT1614A. Here

There can be problems in cases where the OTT is taken, but not formally notified.

Disadvantages

The benefit of taking the OTT is the ability to reclaim input tax which would otherwise fall to be irrecoverable. However, one disadvantage is that opting the sale or rent of a property may reduce its marketability as it is likely that entities which are unable to recover VAT would be less inclined to purchase or lease an opted property.

Another is that the payment of VAT by the purchaser may necessitate obtaining additional funding. This may create problems, especially if a VAT charge was not anticipated. Even though, via opting, the VAT charge is usually recoverable, it still has to be funded up front.

Also, an OTT will increase the amount of SDLT payable when a property is sold. This is always an absolute cost.
Transfer Of a Going Concern (TOGC)

I always say that advice should be taken in all property transactions and also in cases of a Transfer of A business as a Going Concern (TOGC). This is doubly important where an opted building is being sold, because TOGC treatment only applies to a sale of property when specific tests are met.

Property transactions are high value and often complex. The cost of getting VAT wrong, or overlooking it can be very swingeing indeed. I have also seen deals being aborted over VAT issues.  For these reasons, please seek VAT advice at an early stage of negotiations.

More on our land and property services here

Announcement

By   11 September 2015

MASTER LOGO - LARGE:Layout 1Marcus Ward Consultancy Ltd is pleased to announce the acquisition of the professional services practice of the consultancy called: VATAdvice.  This longstanding and highly regarded practice based in Cambridgeshire is owned by Les Howard a well-known face in the VAT world.  Les will continue his VAT support for charities and involvement with the Tax Tribunal.

Director Marcus Ward commented “There is a definite synergy between the two companies and I am pleased that I can continue to help Les’ clients with the highest level of service that I know they have been accustomed to.  This will expand the practice’s existing offering to accountancy and legal firms. We are able to continue to offer VAT advice in the specific areas of; land and property, international transactions, and not for profit bodies as well as dealing with any other VAT issues. We are happy that Les has chosen us to carry on looking after his numerous clients and we aim to make the handover as smooth as possible for all of them”.

Marcus Ward Consultancy Ltd was formed two years ago to help businesses through the increasingly complex VAT regime. It has grown quickly in London and East Anglia and has clients across the world. It is a professional practice committed to providing the highest quality indirect tax advice in a timely and understandable way.  It has expertise in both EC and UK legislation and over 25 years of indirect tax experience.

It is extremely commercially minded and works on the principle of “Leave VAT to us and you can concentrate on growing your business”.

It prides itself in defending businesses against unfair attacks from HMRC.

Enquires: marcus.ward@consultant.com

Telephone: 07748 117935


Charities and VAT

By   7 September 2015

Overview

Surely charities don’t have to pay taxes?

This is a common myth, and while charities do enjoy some VAT reliefs, they are also liable for a number of VAT charges.

Charities have a very hard time of it in terms of VAT, since not only do they have to contend with complex legislation and accounting (which other businesses, no matter how large or complicated do not) but VAT represents a real and significant cost.

By their very nature, charities carry out “non-business” activities which means that VAT is not recoverable on the expenses of carrying out these activities.  Additionally, many charities are involved in exempt supplies, eg; fundraising events, property letting, and certain welfare and educational services, which also means a restriction on the ability to recover VAT on attributable costs.

These two elements are distinct and require separate calculations which are often very convoluted.  The result of this is that charities bear an unfair burden of VAT, especially so since the sector carries out important work in respect of; health and welfare, poverty, education and housing etc.  Although there are some specific reliefs available to charities, these are very limited and do not, by any means, compensate for the overall VAT cost charities bear.

Another issue is legal uncertainty over what constitutes “business income” for charities, especially the VAT status of grants.  It’s worth bearing in mind here the helpful comment in the EC case of Tolsma translated as: “…the question is whether services carried on by [a person] were carried on for the payment or simply with the payment”.

Many charities depend on donations which, due to the economic climate have fallen in value at a time when there is a greater demand on charities from struggling individuals and organisations.

What can be done?

  • Ensure any applicable reliefs are taken advantage of.
  • If significant expenditure is planned, ensure that professional advice is sought to mitigate any tax loss.
  • Review the VAT position to ensure that the most appropriate partial exemption methods and non-business apportionment is in place.
  • Review any land and property transactions. These are high value and some reliefs are available. Additionally it is possible to carry out planning to improve the VAT position of a property owning charity.
  • Review VAT procedures to ensure that VAT is declared correctly. Penalties for even innocent errors have increased recently and are incredibly swingeing.
  • Consider a VAT “healthcheck” which often identifies problems and planning opportunities.

We have considerable expertise in the not for profit sector and would be pleased to discuss any areas of concern, or advise on ways of reducing the impact of VAT on a charity.

More detail on VAT and Charities for guidance

Business activities

It is important not to confuse the term ‘trading’ as frequently used by a charity to describe its non-charitable commercial fund-raising activities (usually carried out by a trading subsidiary) with ‘business’ as used for VAT purposes. Although trading activities will invariably be business activities, ‘business’ for VAT purposes can have a much wider application and include some or all of the charity’s primary or charitable activities.

Registration and basic principles

Any business (including a charity and NFP entity or its trading subsidiary) that makes taxable supplies in excess of the VAT registration threshold must register for VAT. Taxable supplies are business transactions that are liable to VAT at the standard rate, reduced rate or zero rate.

If a charity’s income from taxable supplies is below the VAT registration threshold it can voluntarily register for VAT but a charity that makes no taxable supplies (either because it has no business activities or because its supplies or income are exempt from VAT) cannot register.

Charging VAT

Where a VAT-registered charity makes supplies of goods and services in the course of its business activities, the VAT liability of those supplies is, in general, determined in the normal way as for any other business. Even if VAT-registered, a charity should not charge VAT on any non-business supplies or income.

Reclaiming VAT

This is a two stage process. The first stage in determining the amount of VAT which a VAT-registered charity can reclaim is to eliminate all the VAT incurred that relates to its non-business activities. It cannot reclaim any VAT it is charged on purchases that directly relate to non-business activities. It will also not be able to reclaim a proportion of the VAT on its general expenses (eg; telephone, IT and electricity) that relate to those non-business activities.

Once this has been done, the remaining VAT relating to the charity’s business activities is input tax.

The second stage: It can reclaim all the input tax it has been charged on purchases which directly relate to standard-rated, reduced-rated or zero-rated goods or services it supplies.

It cannot reclaim any of the input tax it has been charged on purchases that relate directly to exempt supplies.

It also cannot claim a proportion of input tax on general expenses (after adjustment for non-business activities) that relates to exempt activities unless this amount, together with the input tax relating directly to exempt supplies, is below the minimis limit.

Business and non-business activities

An organisation such as a charity that is run on a non-profit-making basis may still be regarded as carrying on a business activity for VAT purposes. This is unaffected by the fact that the activity is performed for the benefit of the community. It is therefore important for a charity to determine whether any particular transactions are ‘business’ or ‘non-business’ activities. This applies both when considering registration (if there is no business activity a charity cannot be registered and therefore cannot recover any input tax) and after registration.  If registered, a charity must account for VAT on taxable supplies it makes by way of business. Income from any non-business activities is not subject to VAT and affects the amount of VAT reclaimable as input tax.

‘Business’ has a wide meaning for VAT purposes based upon Directive 2006/112/EC (which uses the term ‘economic activity’ rather than ‘business’), UK VAT legislation and decisions by the Courts and VAT Tribunals.  An activity may still be business if the amount charged does no more than cover the cost to the charity of making the supply or where the charge made is less than cost. If the charity makes no charge at all the activity is unlikely to be considered business.

An area of particular difficulty for charities when considering whether their activities are in the course of business is receipt of grant funding.

Partial Exemption

The VAT a business incurs on running costs is called input tax.  For most businesses this is reclaimed on VAT returns from HMRC if it relates to standard rated or zero rated sales that that business makes.  However, a business which makes exempt sales may not be in a position to recover all of the input tax which it incurred.  A business in this position is called partly exempt.  Generally, any input tax which directly relates to exempt supplies is irrecoverable.  In addition, an element of that business’ general overheads are deemed to be in part attributable to exempt supplies and a calculation must be performed to establish the element which falls to be irrecoverable.

Input tax which falls within the overheads category must be apportioned according to a so called; partial exemption method.  The “Standard Method” requires a comparison between the value of taxable and exempt supplies made by the business.  The calculation is; the percentage of taxable supplies of all supplies multiplied by the input tax to be apportioned which gives the element of VAT input tax which may be recovered.  Other partial exemption methods (so called Special Methods) are available by specific agreement with HMRC.

My flowchart may be of use: partial exemption flowchart 

De Minimis

There is however relief available for a business in the form of de minimis limits.  Broadly, if the total of the irrecoverable directly attributable (to exempt suppliers) and the element of overhead input tax which has been established using a partial exemption method falls to be de minimis, all of that input tax may be recovered in the normal way.  The de minimis limit is currently £7,500 per annum of input tax and one half of all input tax for the year.  As a result, after using the partial exemption method, should the input tax fall below £7,500 and 50% of all input tax for a year it is recoverable in full.  This calculation is required every quarter (for businesses which render returns on a quarterly basis) with a review at the year end, called an annual adjustment carried out at the end of a business’ partial exemption year.  The quarterly de minimis is consequently £1,875 of exempt input tax.

Should the de minimis limits be breached, all input tax relating to exempt supplies is irrecoverable.

Summary

One may see that this is a complex area for charities and not for profit entities to deal with. Certainly a review is almost always beneficial, as are discussions regarding partial exemption methods.

Please click here for more information on our services for charities.

VAT Reliefs for Charities. A brief guide.

By   3 August 2015

Charity and Not For Profit entities – a list of VAT reliefs.

Unfortunately, charities have to contend with VAT in much the same way as any business. However, because of the nature of a charity’s activities, VAT is not usually “neutral” and becomes an additional cost. VAT for charities often creates complex and time consuming technical issues which a “normal” business does not have to consider.

There are only a relatively limited number of reliefs specifically for charities and not for profit bodies, so it is important that these are taken advantage of. These are broadly:

    • Advertising services received by charities;
    • Purchase of qualifying goods for medical research, treatment or diagnosis;
    • New buildings constructed for residential or non-business charitable activities;
    • Self-contained annexes constructed for non-business charitable activities;
    • Building work to provide disabled access in certain circumstances;
    • Building work to provide washrooms and lavatories for disabled persons;
    • Supplies of certain equipment designed to provide relief for disabled or chronically sick persons;

There are also special exemptions available for charities:

    • Income from fundraising events;
    • Admissions to certain cultural events and premises;
    • Relief from “Options to Tax” on the lease and acquisition of buildings put to non-business use.
    • Membership subscriptions to certain public interest bodies and philanthropic associations;
    • Sports facilities provided by non-profit making bodies;

The reduced VAT rate (5%) is also available for charities in certain circumstances:

    • Gas and electricity in premises used for residential or non-business use by a charity;
    • Renovation work on dwellings that have been unoccupied for over two years;
    • Conversion work on dwellings to create new dwellings or change the number of dwellings in a building;
    • Installation of mobility aids for persons aged over 60.

Although treating certain income as exempt from VAT may seem attractive to a charity, it nearly always creates an additional cost as a result of the amount of input tax which may be claimed being restricted. Partial exemption is a complex area of the tax, as are calculations on business/non-business activities which fundamentally affect a charity’s VAT position. I strongly advise that any charity seeks assistance on dealing with VAT to ensure that no more tax than necessary is paid.  Charities have an important role in the world, and it is unfair that VAT should represent such a burden and cost to them.

VAT – Intrastat; what is it? If you don’t know, you may be committing a criminal offence…

By   15 July 2015

Although often viewed as a necessary evil, Intrastat can be used by a business to obtain valuable information on markets in the EC. …Oh, and it may be quite useful to understand it to avoid getting a criminal record!  In this article I summarise the basics, provide useful links and look at the pros and cons of the regime.

So, what is Intrastat?

Intrastat is the name given to the system used for collecting statistics on the trade in goods between all 28 Member States of the EC. If certain conditions are met a business must, by law, submit monthly Intrastat Supplementary Declarations (SDs). Intrastat does not cover services, nor is it required for exports to recipients outside the EC.

The data collected under the Intrastat system forms a large part of overall UK trade statistics totals which in turn are an important part of the UK Balance of Payment account and an important indicator of the health of ‘UK plc’. This data is published at uktradeinfo and is used by a wide range of government and international organisations and is particularly useful in helping businesses gauge import penetration and establish new markets for their goods.

Intrastat responsibilities

If a VAT registered business trades with any of the other EC Member States, it will have a responsibility to report the trade to HMRC. How detailed that report is required to be depends on the value of its trade with other EC Member States for either purchases (arrivals) or sales (dispatches). If a business’ trade in goods falls below the Intrastat thresholds then EC Sales Lists may be required.

Reporting Thresholds for SDs

The limits are:

  • £1,500,000 for arrivals, and;
  • £250,000 for dispatches

In a calendar year.

Intrastat should not be confused with EC Sales Lists which are used to collect information on all sales from UK VAT registered businesses to business recipients in other EC Member States.  A guide to EC Sales Lists here

Classification of goods for Intrastat

Finding the right commodity code for goods is one of the most important aspects of Intrastat. An online classification tool, the Intrastat Classification Nomenclature (ICN) is available to assist businesses find the right commodity code for its goods. Here

The ICN is a fully searchable facility which can be used by everyone from beginner to expert.

Value for SDs

Only the value of goods are included in SDs (plus any related freight or insurance charges where they form part of the invoice or contract price of the goods).

The value does not include:

  • Commission, legal and financial services
  • Insurance, freight and/or carriage (unless it is included with the cost of the goods)
  • Labour
  • Goods bought and sold within the EU but which do not actually enter or leave the UK
  • Maintenance costs
  • Repairs

Submission of SDs

This may be done online or offline (which is preferred for large amounts of data).

Online submission details here

Offline submissions are via pre-prepared Excel spreadsheets available here

Via an email attachment – the file must be converted into the message format Electronic Data Interchange for Commerce and Transport (EDIFACT). Details here

Deadlines for submission of SDs

Intrastat declarations must be submitted on a monthly basis. Complete and accurate declarations must be received by the 21st day of the month following the reference period to which they relate.

Now, the scary part.

Penalties

It is perhaps surprising that if you fail to submit SDs by the due date, or send data that is inaccurate, a business will be committing a criminal offence (Statistics of Trade [C&E] Regulations 1992).

Penalties may be levied in cases where SDs are persistently late, missing, inaccurate or incomplete.

Although the penalty regime is a criminal one and could result in proceedings in a Magistrates Court, HMRC state that it normally prefers to “compound” alleged offences. This involves the offer of an administrative fine in lieu of Court proceedings. However, an administrative fine is only offered when, after receiving a Warning of Possible Criminal Proceedings letter, a business has brought its Intrastat declarations completely up to date. If any declarations remain outstanding Court proceedings will be instigated.

The plus side.

How to use Intrastat for your business

It is possible for a business to find out about; trade markets, competition, suppliers, customers and competitors using data collected via Intrastat.  Additionally, the information may be used to create a bespoke data table to suit a business’ specific needs. Information here

Intrastat pros and cons

Yes, businesses are being used as unpaid providers of trade information as well as unpaid collectors of tax.  It then does seem rather draconian that HMRC “coerce” businesses to provide information on pain of a criminal record. But the information is then there for a business trading within the EC to use for its commercial advantage.  It’s another chore on the VAT checklist I’m afraid.

VAT – Retrospective input tax claim opportunity for charities and not for profit bodies.

By   22 June 2015

The Upper Tribunal has decided In the University Of Cambridge case that costs incurred on running its endowment fund relate to the university’s overall economic activity in general and consequently it is possible to recover an element of it.  The full judgement here

This will impact on all charities and similar bodies which have non-business activities that support their business activities. 

Please contact us if your charity is in a similar position because if past input tax claims have been restricted as a result of HMRC’s interpretation (which is highly likely) it is possible to make a claim which covers the last four years’ VAT costs.

VAT – The Future for the EC Digital Single Market

By   11 May 2015

VAT – The Future for the EC Digital Single Market

The EC has announced its plans for its VAT digital single market in respect of online sales. Full details are here and here.

The highlights are:

• Extension of MOSS to intra-EC and third country online B2C sales of goods.

• Introduction of a new EC-wide VAT threshold to help start-up businesses.

• Ending current distance selling thresholds.

• Allowing for domestic controls, including a single audit of cross-border sales.

• Removal of the VAT exemption for the import of small consignments form third countries.

• Removal of barriers to cross-border sales eg; geo-blocking and costs.

This is likely to have a huge impact on the way businesses deal with VAT on sales of goods to individuals overseas. If the introduction of MOSS is anything to go by, we may be in for a bumpy ride.

VAT – Business Entertainment Flowchart. What input tax may I recover?

By   11 May 2015

VAT – Recovery of input tax incurred on entertainment

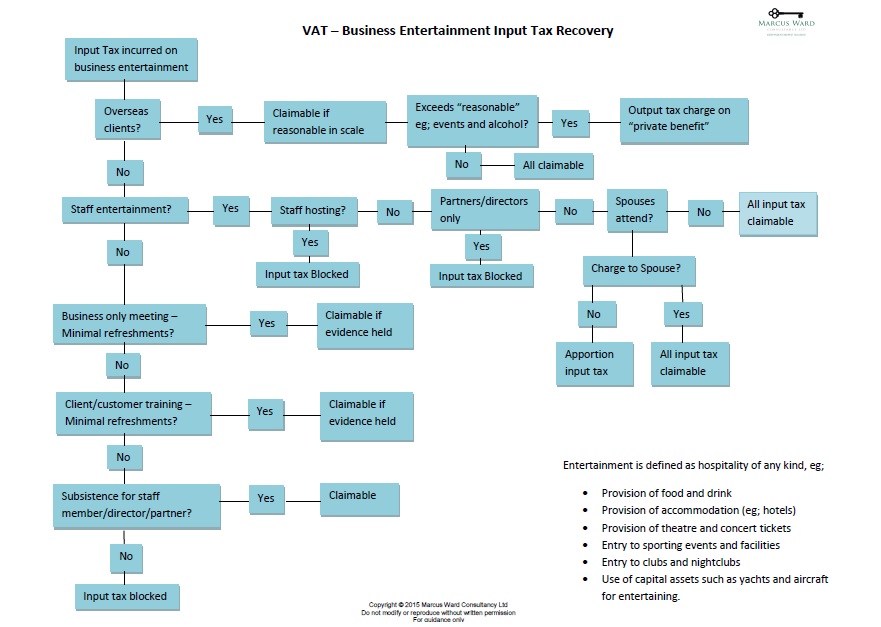
One of the most common questions asked on “day-to-day” VAT is whether input tax incurred on entertainment is claimable.  The answer to this seemingly straightforward question has become increasingly complex as a result of; HMRC policy, EC involvement and case law.  Different rules apply to entertaining; clients, contacts, staff, partners and directors depending on the circumstances.  It seems reasonable to treat entertaining costs as a valid business expense.  After all, a business, amongst other things, aims to increase sales and reduce costs as a result of these meetings.  However, HMRC sees things differently and there is a general block on business entertainment.  It seems like HMRC does not like watching people enjoying themselves at the government’s expense!

If, like me, you think in pictures, then a flowchart may be useful for deciding whether to claim entertainment VAT.  It covers all scenarios, but if you have a unique set of circumstances or require assistance with some of the definitions, please contact me.

I thank my friend and colleague Leila Ong for help with this, and also with the series of presentations we have recently carried out and which, amongst other subjects, covered business entertainment. Should you require VAT training or presentations, don’t forget our comprehensive service here which can be tailored to your needs.

VAT -Business Entertainment Flowchart

Business Entertainment flow chart

Download here: VAT Business Entertainment Input tax recovery flowchart

VAT: Global Accounting simplification

By   27 April 2015

VAT: Second Hand Scheme  – Global Accounting simplification

Overview

The problem with the VAT Second-Hand Goods Scheme is that details of each individual item purchased, and then later sold, has to be recorded. This requirement can lead to a lot of paperwork and an awful lot of administration which, obviously, many businesses are not too keen to comply with.

Global Accounting is an optional, simplified variation of the Second Hand Margin Scheme (Margin Scheme).

It differs from the standard Margin Scheme because rather than accounting for the margin achieved on the sale of individual items VAT is calculated on the margin achieved between the total purchases and total sales in a particular accounting period without the requirement to establish the mark up on each individual item.  It is beneficial if a business buys and sells bulk volume, low value eligible goods, and is unable to maintain the detailed records required of businesses who use the standard Margin Scheme

There two significant differences in respect of Global Accounting compared to the standard Margin Scheme. The first difference is that losses on an item are automatically offset against profits on items. Thus losses and profits are offset together in the period. In the standard Margin Scheme no VAT is due if a loss is made on an item, but that loss cannot be offset against any other profit.  There is also a timing advantage with Global Accounting because all purchases made in the period are included, even if those goods are not actually sold in the same period.

Goods which may be included in Global Accounting

Global Accounting can be used for all items which are eligible under the standard Margin Scheme.  However, the following goods cannot be included in Global Accounting:

  • individual items costing more than £500 (although these can be accounted for via the standard Margin Scheme)
  • aircraft, boats and outboard motors,
  • caravans and motor caravans,
  • horses and ponies, and
  • motor vehicles, including motorcycles; except those broken up for scrap.

Starting to use the scheme

When a business starts using Global Accounting, it may find that it already has eligible stock on hand.  It may include the value of this stock when it calculates the total purchases at the end of the first period.  If a business does not take its stock on hand into account, it will have to pay VAT on the full price, rather than on the margin achieved, when it is sold.

Valuation of stock

A business must be able to identify:

  • stock which is eligible for Global Accounting, and
  • its purchase value

It would normally be possible to establish the value from the original purchase documentation, ie; invoices.

But if a business is newly VAT registered, or it does not have original purchase records it may determine the purchase value using another method.   There is no set way of doing this, but a business must be able to demonstrate that the method used has produced a fair and reasonable total.

Note: any goods bought on an invoice which shows a separate VAT figure are not eligible for resale under the scheme.

The calculation

VAT is calculated at the end of each tax period. Because you can take account of opening stock in your scheme calculations, you may find that you produce a negative margin at the end of several periods. In other words, your total purchases may exceed your total sales. In such cases, no VAT is due. But you must carry the negative margin forward to the next period as in the following example:

Period One

a)      Total purchase value of stock on hand 10,000

b)      Total purchases 2,000

c)      Total sales 8,000

Margin = c – (a+b) = (4,000)

Because this is a negative margin there is no VAT to pay.  However, negative margin must be carried forward into the next period as follows:

Period Two

a)      Negative margin from previous period 4,000

b)      Total purchases 1,000

c)      Total sales 7,000

d)      Margin = c – (a + b), sales minus (purchases plus negative margin), £7,000 – (£1,000 + £4,000) 2,000

e)      VAT due = margin (£2,000) × VAT fraction (1/6) 333.33

There is no negative margin to carry forward this time. Therefore, in the third period, the margin is calculated solely by reference to sales less purchases.

The negative margin may only be offset against the next Global Accounting margin. It cannot be offset against any other figure or record.

Global Accounting Records and Accounts

A business does not need to keep all the detailed records which are required under the normal Margin Scheme – for instance, you do not have to maintain a detailed stock book.

Global Accounting records do not have to be kept in any set way but they must be complete, up to date and clearly distinguishable from any other records.  A business must keep records of purchases and sales as set out below, together with the workings used to calculate the VAT due.

If we HMRC cannot check the margins declared from the records, VAT will be due on the full selling price of the goods sold, even if they were otherwise eligible for the scheme.

Buying goods under Global Accounting

When a business buys goods which it intends to sell under Global Accounting it must:

  • check that the goods are eligible for Global Accounting
  • obtain a purchase invoice. If a business buys from a private individual or an unregistered entity, the purchaser should make out the invoice at the time the goods are purchased.  If purchased from another VAT-registered dealer, the dealer must make out the invoice at the time of sale, and
  • enter the purchase details of the goods in your Global Accounting purchase records.  The purchase price must be the price on the invoice which has been agreed between you and the seller.

You cannot use the scheme if VAT is shown separately on the invoice.

Details to be included on purchase invoices

 Purchase invoices must include:

your name and address

  • the seller’s name and address
  • invoice number
  • date of transaction
  • description of goods (this must be sufficient to enable HMRC to verify that the goods are eligible for Global Accounting)
  • total price, you must not show VAT separately, and
  • for goods purchased from another VAT-registered dealer: the statement “Global Accounting Invoice”

Remember: if you are buying from a private individual or an unregistered business, you must make out the purchase invoice yourself.

When selling goods under Global Accounting

If the purchase conditions above apply, Global Accounting may be used when the goods are sold by:

  • recording the sale in the usual way
  • issuing a sales invoice for sales to other VAT-registered dealers and keeping a copy of the invoice, and
  • transferring totals of copy invoices to the Global Accounting sales record or summary
  • you must be able to distinguish at the point of sale between sales made under Global Accounting and other types of transaction

Details to be included on sales invoices

 A sales invoice must be issued to other VAT-registered customers.  These invoices and any other Global Accounting sales invoice issued must show the following details:

  •  your name, address and VAT registration number
  • the buyer’s name and address
  • invoice number
  • date of sale
  • description of goods (this must be sufficient to enable HMRC to verify that the goods are eligible for Global Accounting)
  • total price – you must not show VAT separately
  • the statement “Global Accounting Invoice”
  • you are selling an item for more than £500 and you don’t want the purchaser to know that you bought it under Global Accounting, you may use one of the Margin Scheme sales invoice statements.

 Details to be included in purchase and sales summaries

 Although a business does not have to keep purchase and sales records or summaries in any particular way, they must include the following details taken from the purchase invoices and any sales invoices you issue:

  •  invoice number (where the purchase invoice shows one)
  • date of purchase/sale
  • description of goods, and total price

 Cessation of using the scheme

If a business stops using Global Accounting for any reason, it must make a closing adjustment to take account of purchases for which it has taken credit, but which have not been sold (closing stock on hand). The adjustment required does not apply if the total VAT due on stock on hand is £1,000 or less. In the final period for which the business uses the scheme, it must add the purchase value of its closing stock to the sales figure for that period.  In this way VAT will be paid (at cost price) on the stock for which the business previously had credit under the scheme.

Here is an example of a closing adjustment under Global Accounting: At the end of the period calculate:

(a)    value of purchases during the period – £5,000

(b)    value of sales during the period – £10,000

(c)    purchase value of closing stock – £8,000

(d)    add purchase value of closing stock to sales for period (c+b) – £18,000

(e)    subtract purchases in this period from sale (d-a) – £13,000

(f)     VAT due on margin (e x 1/6) – £2,166.66

You must make a similar adjustment if you transfer goods as part of a transfer of a going concern (TOGC). In that case, you should add the purchase value of goods included in the scheme to your sales figure for the period in which the TOGC takes place.  This adjustment is separate from the TOGC itself, which is not subject to VAT.

Items sold outside the scheme

If goods are sold which had been included in a business’ Global Accounting purchase (for example, they are exported), a business must adjust its records accordingly.  This is done by subtracting the purchase value of the goods sold outside the scheme from the total purchases at the end of the period.

Stolen or destroyed goods

If a business loses any goods through breakage, theft or destruction, it must subtract their purchase price from your Global Accounting purchase record.

Repairs and restoration costs?

A business may reclaim the VAT it is charged on any business overheads, repairs, restoration costs, etc. But it must not add any of these costs to the purchase price of the goods sold under the scheme.

EC Sales List, Intrastat and VAT returns

VAT registered businesses in the UK who make supplies of goods to VAT-registered businesses in other EC Member States are required to complete lists (form VAT 101) of their EC supplies.

But a business should not include any margin schemes transactions on an EC Sales list because they will be subject to VAT in the UK.

Intrastat is the system for collecting statistics on the trade in goods between EC Member States. But, because margin scheme goods are subject to VAT in the country of origin, there is no requirement either:

  • to include margin scheme purchases or sales in boxes 8 and 9 of your VAT return, or
  • to complete a supplementary declaration

For further advice on any global accounting, used goods schemes, or any other special VAT schemes please contact me.

© Marcus Ward Consultancy Ltd