Tag Archives: VAT-POS

VAT: What is a taxable supply? – Definition

By   8 September 2026

VAT Basics

Taxable supply

It is sometimes useful when considering a transaction to “go back to basics” for VAT purposes. There are certain tests to determine whether a supply is taxable, and these are set out below. Broadly, the tests establish whether UK VAT is payable on a sale and they determine whether an entity is “in business”, that is; carrying on an economic activity.

A transaction is within the scope of UK VAT if all four of the following conditions are satisfied:

  • It is a supply of goods or services.

There is a distinction between the two types of supply as different VAT treatments may apply.  Generally, everything that is not tangible goods is services. However, if no goods or services are actually provided, there is no supply.  Indeed, if there is no consideration for a supply, in most cases it is not a taxable supply.

  • It takes place in the UK.

There are quite complex tests to consider when analysing the “place of supply”, especially where services are concerned.  If the place of supply is outside the UK then usually no UK VAT is due, however, the supply may be subject to VAT in another country.

  • It is made by a taxable person.

A taxable person is any legal entity which is, or should be, registered for VAT in the UK.

  • It is made in the course or furtherance of any business carried on by that person

Business

The term “business” is only used in UK legislation, The Principal VAT Directive refers to “economic activity” rather than “business” and since UK domestic legislation must (well historically) conform to the Directive both terms must be seen as having the same meaning.  Since the very first days of VAT there have been disagreements over what constitutes a “business”. I have only recently ended a dispute over this definition for a (as it turns out) very happy client. The tests were set out as long ago as 1981 and may be summarised as follows:

  • Is the activity a serious undertaking earnestly pursued?
  • Is the activity an occupation or function, which is actively pursued with reasonable or recognisable continuity?
  • Does the activity have a certain measure of substance in terms of the quarterly or annual value of taxable supplies made (bearing in mind that exempt supplies can also be business)?
  • Is the activity conducted in a regular manner and on sound and recognised business principles?
  • Is the activity predominantly concerned with the making of taxable supplies for a consideration?
  • Are the taxable supplies that are being made of a kind which, subject to differences of detail, are commonly made by those who seek to profit from them?

So, if these tests are passed a taxable supply exists. The next step is to establish which VAT rate applies. In an often quoted comment from the judge in the Morrison’s Academy Boarding Houses Association 1978 STC1 Court Of Session case “…In my opinion it will never be possible or desirable to define exhaustively ‘business’ ”. Which what it lacks in helpfulness, makes up for in candour.

There was something of a deviation from the Lord Fisher tests in the Longbridge Court of Appeal case, however, that appears to be a blip and HMRC seem to have reverted to Lord Fisher in subsequent hearings on the same topic. A bit of a: watch this space area of VAT.

Recent cases on business

Recent case law on this issue here and here and HMRC Internal guidance on the Lord Fisher tests here

Commentary

Tip: It is often easier to consider what isn’t a taxable supply to establish the correct VAT treatment.  Specific examples of situations which are not taxable supplies are; donations, certain free supplies of services, certain grants or funding, some compensation and some transactions which are specifically excluded from the tax by legislation, eg; transfers of going concerns (TOGC).

I think that it is often the case that the basic building blocks of the tax are overlooked, especially in complex situations and I find it helps to “go back to the first page” sometimes.

VAT: Where do I belong?

By   11 June 2026
The place of belonging

The concept of “belonging” is very important in VAT as it determines where a supply takes place and thus the rate applicable and the country in which is due. (The so-called “Place Of Supply, or POS). It is necessary, for most supplies, to establish where both the supplier, and the recipient belongs. Because this is a complex area of VAT it is not difficult to be overpaying tax in one country, not paying tax where it is properly due, or missing the tax issue completely.

A relevant business person `belongs’ in the relevant country. A `relevant country’ means:

  • the country in which the person has a business establishment, or some other fixed establishment (if it has none in any other country);
  • if the person has a business establishment, or some other fixed establishment or establishments, in more than one country, the country of the relevant establishment (ie; the establishment most directly concerned with the supply); and
  • otherwise, the country of the person’s usual place of residence (in the case of a body corporate, where it is legally constituted)

A person who is not a relevant business person `belongs’ in the country of his usual place of residence. The `belonging’ definition applies equally to a supplier and the recipient of a supply, where relevant.

Business establishment is not defined in the legislation but is taken by HMRC to mean the principal place of business. It is usually the head office, headquarters or ‘seat’ from which the business is run. There can only be one such place and it may take the form of an office, showroom or factory.

Fixed establishment is also not defined in the legislation but is taken by HMRC to mean an establishment (other than the business establishment) which has both the technical and human resources necessary for providing and receiving services on a permanent basis. A business may therefore have several fixed establishments, including a branch of the business or an agency. A temporary presence of human and technical resources does not create a fixed establishment in the UK.

Usual place of residence. A body corporate has its usual place of residence where it is legally constituted. The usual place of residence of an individual is not defined in the legislation. HMRC interpret the phrase according to the ordinary usage of the words, ie; normally the country where the individual has set up home with his/her family and is in full-time employment. An individual is not resident in a country if only visiting as a tourist.

More than one establishment. Where the supplier/recipient has establishments in more than one country, the supplies made from/received at each establishment must be considered separately. For each supply of services, the establishment which is actually providing/receiving the services is normally the one most directly connected with the supply but all facts should be considered including

  • for suppliers, from which establishment the services are actually provided
  • for recipients; at which establishment the services are actually consumed, effectively used or enjoyed
  • which establishment appears on the contracts, correspondence and invoices
  • where directors or others who entered into the contract are permanently based, and
  • at which establishment decisions are taken and controls are exercised over the performance of the contract

However, where an establishment is actually providing/receiving the supply of services, it is normally that establishment which is most directly connected with the supply, even if the contractual position is different.

VAT groups

A VAT group is treated as a single entity. This also applies when applying the ‘place of belonging’. As a result, a group has establishments wherever any member of the group has establishments.

This is an area which often leads to uncertainty, and therefore VAT issues.  It is also an area where VAT planning may; save time, resources and avoid unexpected VAT costs, either in the UK or another country.

For more on our International Services

VAT: New guidance – Online Marketplace supplies

By   24 June 2025

HMRC issued new guidance for businesses which sell goods using an online marketplace on 20 June 2025. It enables online marketplace (an e-commerce site that connects sellers with buyers where transactions are managed by the website owner) operators to check if a seller is established outside the UK, so that it can establish which party is liable for VAT on sales.

Background

An online marketplace operator is liable for VAT on goods of any value that are both:

  • located in the UK at the point of sale
  • sold by an overseas business through the operator’s online marketplace

The operator needs to establish who is liable for VAT on sales of goods which are facilitated. To confirm this, the operator needs to take all reasonable steps to check whether a seller is established outside the UK. A business is required to keep evidence to show that it has taken all reasonable steps.

This new guidance includes details about how to check where an online marketplace seller is established and provides information about checks and process businesses can put in place. HMRC will review this evidence and will consider all evidence which has been used to establish where the seller is established. In each case, it will consider:

  • what steps were performed, including any that are designed to address the risks of a particular case
  • to what extent steps were appropriate, adequate and timely in relation to addressing the risks identified
  • what the results of the checks indicate
  • whether a business took appropriate action in response to the results

Examples of checks

HMRC give the following examples of types of checks which might be undertaken to determine if an online seller is UK-established:

  • check for a UK principal place of business
  • check that the VAT registration available for the seller matches their legal name and details on HMRC’s Check a UK VAT number tool
  • check that the seller is registered at Companies House with a UK address
  • establish whether directors reside in the UK, eg; as shown on the Companies House register
  • check that payment or financial information shows a UK presence. This can include:
    • UK bank or credit card details
    • UK merchant address attached to the seller bank account
    • other financial data provided by independent payment service providers
  • check other commercially relevant information such as credit checks and other background checks from third party sources
  • check that the device used by the seller has a UK IP address, or check another method of geolocation
  • establish whether the seller uses a phone number with a UK country code

Overview of online sellers

More general guidance from HMRC on online sellers:

The rules aim to avoid VAT evasion by non-UK online sellers.

What is outside the scope of VAT, and what does it mean?

By   10 January 2025

Put simply, income which is outside the scope (OSC) of VAT is UK VAT free. It means that either there has been no supply in respect of that income (non-business, or ‘NB’), or if there is, it has a place of supply (POS) which is outside the UK. Although VAT free, OSC is distinct from exempt or zero-rated supplies and has a different impact for the entity involved in NB activities.

So, here I consider the different types of OSC income and how it affects the VAT position of the recipient of such a payment.

Charity

Charities and NFP organisations often receive income from various sources and often receive NB income which is OSC. This income is often donations for which the donor does not receive anything (there is no consideration provided by the charity). An organisation such as a charity that is run on a non-profit-making basis may still be regarded as carrying on a business activity for VAT purposes. This is unaffected by the fact that the activity is performed for the benefit of the community. It is therefore important for a charity to determine whether particular transactions are business or NB activities. This applies both when considering registration (if there is only NB activity a charity cannot be registered and therefore cannot recover any input tax) and after registration. ‘Business’ has a wide meaning for VAT purposes – an activity may still be business if the amount charged does no more than cover the cost to the charity of making the supply or where the charge made is less than cost. If the charity makes no charge at all the activity is unlikely to be considered business. A common area of complexity for charities when considering whether their activities are in the course of business is receipt of grant funding (please see below).

Grants 

There is no ‘standard’ VAT treatment of grants. The VAT outcome depends on the precise facts of each specific agreement. The most important test is whether the grantor receives any consideration in return for the payment. It may be that the donor recognises the good work a body does and wishes to contribute (akin to a donation) which is OSC. Alternatively, the recipient of the grant may be obliged to provide something in return (a supply which is not OSC). A helpful way of looking at this is to consider, not what the recipient does with grant money, but what it does for it.

Inter-company charges

Charges between VAT group members are OSC. Moreover, charges between non-VAT-grouped companies may also be OSC. These are commonly called ‘management charges’ and the VAT treatment depends on a number of facts. It is often the case that a management charge is used as a mechanism for transferring “value” from one company to another. If it is done in an arbitrary manner with no written agreement in place, and nothing identifiable is provided the income is likely to be OSC. Otherwise, it is likely to be a taxable supply. What is important is not how a management charge is calculated, but what the supply actually is (if it is one). The calculation, whether based on a simple pro-rata amount between separate subsidiaries, or via a complex mechanism set out in a written agreement has no impact on the VAT treatment. As always in VAT, the basic question is: what is actually provided? 

Place of supply not the UK

If the POS is outside the UK, then the resulting payment for that supply is OSC. The POS rules can be complex and care must be taken in identifying the correct country to declare output tax (this may include the use of the OSS). In some instances, the Reverse Charge is applied. Input tax incurred in relation these supplies is recoverable, subject to the normal rules, and this distinguishes this type of supply from some of the others discussed here.

Transfer Of a Going Concern (TOGC) 

A TOGC is deemed to be neither a supply of goods nor services, so consequently, it is OSC. Input tax incurred in respect of the costs of making a TOGC are considered an overhead of the business for partial exemption purposes, so it is not automatically disallowed because it relates to a ‘non-supply’.

Supplies by a non-taxable person

Sales by a business person who is not liable to be VAT registered.

Insurance etc

A payment between persons, which is paid under a contract of indemnity, is OSC, because it does not represent consideration for a supply, eg; sums paid under an insurance policy.

Private transactions

These transactions between individuals or gifts received are OSC.

Statutory fees

These are OSC, an example of such fees are: the London congestion charge, MOT testing, some road tolls, and parking fines.

Input tax recovery 

VAT incurred on costs directly relating to OSC activities is not input tax and cannot be recovered (there are no de minimis limits). This is separate to partial exemption and a business/NB calculation is required before a partial exemption calculation is carried out, so it is a two-tier exercise. It may be possible to combine these two calculations, but that is an article for another day.

HMRC has issued new guidance on the amount of input tax claimable when an element is attributable to NB activities. If an entity is involved in both business and NB activities, eg; a charity which provides free advice and also has a shop which sells donated goods, it is unable to recover all of the VAT it incurs.  VAT attributable to NB activities is not input tax and cannot be reclaimed.  Therefore, it is necessary to calculate the quantum of VAT attributable to business and NB activities. That VAT which cannot be directly attributed is called overhead VAT and must be apportioned between business and NB activities.  There are many varied ways of doing this as the VAT legislation does not specify any particular method.  It is important to consider all of the available alternatives. Examples of these are; income, expenditure, time, floorspace, transaction count etc (similar to those methods available for partial exemption calculations). Any calculation must be fair and reasonable.

Overall

OSC income should not be recognised in the value box of VAT returns and it does not count towards the VAT registration limit. It is likely to negatively affect the recipient’s input tax recovery position. The distinction between business and non-business is crucial and will significantly impact on an entity’s overall VAT position.

Further reading

The following articles consider case law and other relevant business/NB issues:

Wakefield College

Longbridge

Babylon Farm

A Shoot

Y4 Express

Lajvér Meliorációs Nonprofit Kft. and Lajvér Csapadékvízrendezési Nonprofit Kft

Healthwatch Hampshire CIC 

Pertempts Limited

Northumbria Healthcare

VAT: Zero-rated exports. The Procurement International case

By   7 November 2024

Latest from the courts

In the First-Tier Tribunal (FTT) case of Procurement International Ltd (PIL) the issue was whether the movement of goods constituted a zero-rated export.

Background

Both parties essentially agreed the facts: The Appellant’s business is that of a reward recognition programme fulfiller. The Appellant had a catalogue of available products, and it maintained a stock of the most ordered items in its warehouse. PIL supplied these goods to customers who run reward recognition programmes on behalf of their customers who, in turn, want to reward to their customers and/or employees (reward recipients – RR). The reward programme operators (RPOs) provide a platform through which those entitled to receive rewards can such rewards. The RPO will then place orders PIL for the goods.

A shipper collected the goods from PIL in the UK and shipped them directly to the RR (wherever located). The shipper provided the services of delivery including relevant customs clearances etc. on behalf of the Appellant. PIL had zero-rated the supply of goods sent to RRs located overseas. All goods delivered to RRs outside the UK are delivered duty paid (DDP) or delivered at place (DAP). As may be seen by Incoterms the Appellant remained at risk in respect of the goods and liable for all carriage costs and is responsible for performing or contracting for the performance of all customs (export and import) obligations. The Appellant was responsible for all fees, duties, tariffs, and taxes. Accordingly, the Appellant is responsible for, and at risk until, the goods are delivered “by placing them at the disposal of the buyer at the agreed point, if any, or at the named place of destination or by procuring that the goods are so delivered”.

Contentions

HMRC argued that in situations where the RPO was UK VAT registered, the appellant was making a supply of goods to the RPO at a time when the goods were physically located in the UK, and consequently there was a standard-rated supply. It issued an assessment to recover the output tax considered to be underdeclared.

PIL contended that there was a supply of delivered goods which were zero-rated when the goods were removed to a location outside the UK. It was responsible (via contracts which were accepted to reflect the reality of the transactions) for arranging the transport of the goods.

Decision

The FTT held that there was a single composite supplies of delivered goods, and these were a zero-rated supply of exported goods by PIL. The supplies were not made on terms that the RPOs collected or arranged for collection of the goods to remove them from the UK. The Tribunal found that the RPOs took title to the goods at the time they were delivered to the RR, and not before such that it was PIL and not the RPOs who was the exporter. This meant that the RPOs would be regarded as making their supplies outside the UK and would be responsible for overseas VAT as the Place Of Supply (POS) would be in the country in which it took title to the goods (but that was not an issue in this case).

The appeal was allowed, and the assessment was withdrawn.

Legislation

Domestic legislation relevant here is The VAT Act 1994:

  • Section 6(2) which fixes the time of supply of goods involving removal as the time they are removed
  • Section 7 VATA sets out the basis on which the place of supply is determined. Section 7(2) states that: “if the supply of any goods does not involve their removal from or to the United Kingdom they shall be treated as supplied in the United Kingdom if they are in the United Kingdom and otherwise shall be treated as supplied outside the United Kingdom”.
  • Section 30(6) VATA provides that a supply of goods is zero-rated where such supply is made in the UK and HMRC are satisfied that the person supplying the goods has exported them
  • For completeness, VAT Regulations 1995, regulation 129 provides the framework for the zero-rating goods removed from the UK by and on behalf of the purchaser of the goods.

Some paragraphs of VAT Notice 703 have the force of law which applies here, namely the sections on:

  • direct and indirect exports
  • conditions which must be met in full for goods to be zero-rated as exports
  • definition of an exporter
  • the appointment of a freight forwarder or other party to manage the export transactions and declarations on behalf of the supplier of exporter.
  • the conditions and time limits for zero rating
  • a situation in which there are multiple transactions leading to one movement of goods

Commentary

The Incoterms set out in the relevant contracts were vital in demonstrating the responsibilities of the parties and consequently, who actually exported the goods. It is crucial when analysing the VAT treatment of transactions to recognise each party’s responsibilities, and importantly, when (and therefore where) the change in possession of the goods takes place.

VAT: Electronic Sales Suppression (ESS)

By   3 January 2024

HMRC has published new guidance on ESS and information on how to make a disclosure.

What is ESS?

ESS is also known as till fraud or till manipulation. It is where a business manipulates their till systems to hide or reduce the true value or number of sales. This is carried out through the use of ESS tools such as misusing built in till functions or installing software specifically designed to suppress sales. HMRC call this sales suppression and it is done either at, or after, the point of sale (POS). The records then appear to be correct and complete.

Businesses do this to reduce their turnover so that they pay less tax. They also do this to try to appear compliant.

Misusing a till system reduces the recorded turnover of the business and the amount of VAT payable, whilst providing what appears to be an accurate and complete record.

ESS is tax fraud. You are involved with ESS if you have made, supplied, promoted, possess or have access to an ESS tool.

You are also involved in ESS if:

  • you own an ESS tool
  • have access to an ESS tool
  • have tried to access an ESS tool

What is an ESS tool?

An ESS tool is a piece of software, computer code script or hardware. It allows a business to hide or reduce the value of individual transactions on its electronic sales records. This includes using and/or configuring a till, or point of sale system, in a way that suppresses sales.

You do not have to have used an ESS tool to suppress sales or pay less VAT for HMRC to charge a penalty for being involved in ESS, it is fraud regardless. 

HMRC powers

Finance Act 2022, Schedule 14 allows HMRC to issue an information notice for ESS. This means HMRC can ask for certain information that only applies to ESS. It allows the issue of a Notice to a ‘relevant person’ for a ‘relevant purpose’.

Who is a ‘relevant person’

A ‘relevant person’ is any person who HMRC think it might be able to charge a penalty for being involved in ESS.

What is a ‘relevant purpose’

A ‘relevant purpose’ is the reason that HMRC is asking for information about ESS and ESS Tools. The law allows HMRC to do this in three types of situations which are to help it:

  • decide whether a relevant person has made, supplied, promoted, or possesses an ESS tool — HMRC would be able to charge this person a penalty
  • understand how an ESS tool works
  • identify any other person who has made, supplied, promoted, or possesses the ESS tool

Disclosure

HMRC is offering an opportunity for those involved in ESS to make a disclosure. Early voluntary disclosure could lead to a reduction in financial penalties. Use the ‘Make a disclosure about misusing your till system’ form to tell HMRC that you have been using your till system to reduce your tax bill.

Further reading and more detailed information on penalties here.

VAT: Place of supply – The Sports Invest case

By   5 May 2023

Latest from the courts

In the First-Tier Tribunal case of Sports Invest UK Ltd the issue was the place of supply (POS) of a football agent’s services (commission received for a player’s transfer).

The POS is often complex from a VAT perspective and depends on the place of belonging (POB) of the supplier and the recipient of the supply. These rules determine if VAT is charged, where VAT is charged and the rate of VAT applicable, additionally, they may impose requirements to register for VAT in different jurisdictions.

Background

Sports Invest was a football agent based in the UK. It received fees in respect of negotiating the transfer of a player: João Mário from a Portuguese club: Sporting Lisbon to an Italian club: Internazionale (Inter Milan). The appellant signed a representation contract with the player which entitled it to commission, and a separate agreement with Inter Milan entitling it to a fee because the player was permanently transferred.

The Issues

To whom did Sports Invest make a supply – club or player? What was the supply? Was there one or two separate supplies? What was the POS?

As appears normal for transactions in the world of football the contractual arrangements were complex, but, in essence as a matter of commercial and economic reality, Sports Invest had agreed the commission with the player in case it was excluded from the deal. However, this did not occur, and the deal was concluded as anticipated. Inter Milan paid The Appellant’s fee in full, but did this affect the agreement between Sports Invest and the player? That is, as HMRC contended, did Inter Milan pay Sports Invest on the player’s behalf (third party consideration) such that there were two supplies; one to the player and one to the cub?

The FTT stated that there was no suggestion that the contracts were “sham documents”.

VAT Liability

The arrangements mattered, as pre-Brexit, a supply of services by a business with a POB in the UK to an individual (B2C) in another EU Member State would have been subject to UK VAT; the POS being where the supplier belonged. HMRC assessed for an element of the fee that it saw related to the supply to the player. The remainder of the fee paid by the club was accepted to be consideration for a UK VAT free supply by the agent to the club (B2B).

Decision

The court found that there was one single supply by The Appellant to Inter Milan. This being the case, the supply was B2B and the POS was where the recipient belonged and so that the entire supply was UK VAT free. There was no (UK) supply to the individual player as that agreement was superseded by the contractual arrangements which were actually put in place and the player owed the agent nothing as the potential payment under that contract was waived.

The appeal against the assessment was upheld.

Commentary

The court’s decision appears to be logical as the supply was to the club who were receiving “something” (the employment contract with the player) and paying for it. The other “safeguarding” agreement appeared to be simple good commercial practice and was ultimately “not required”. This case highlights the often complex issues of; establishing the nature of transactions, the identity of the recipient(s), agency arrangements, the POS and the legal, commercial and economic reality of contracts.


VAT: Exemption of fund management services

By   8 February 2023

HM Treasury has published a consultation paper on the treatment of the service of management of special investment funds (SIFs).

SIF meaning in VAT terms

There is no definition of a SIF in existing legislation.

Morgan Fleming Claverhouse Trust plc (case C-363/05) ruled on the interpretation of the term ‘Special Investment Funds as defined by Member States’.

The key points in this judgment are:

  1. the term ‘special investment funds’ is capable of including closed-ended investment funds, such as investment trust companies (ITCs)
  2. Member States have a discretion to define ‘special investment funds’ for the VAT exemption but, in doing so, must pay due regard to:
  3. the purpose of the exemption
  4. the principle of fiscal neutrality.

According to the Court, the purpose of the exemption is to facilitate investment in securities for investors through investment undertakings. This requires there to be VAT neutrality between the direct investment in securities and investment through collective investment undertakings, as the latter incurs a management charge. Furthermore, there must be equality of VAT treatment for funds which are similar to, and in competition with, funds falling within the scope of the exemption.

As a result of the case, the exemption was extended so that there was a level VAT playing field for all similar collective investment undertakings which compete in the UK retail market. This includes closed and open-ended collective investment undertakings, umbrellas and sub-funds, as well as some pension schemes.

The fund management exemption is limited to the management of SIFs. Consequently, the management of other investment funds will generally be standard-rated.

Legislation

The current VAT fund management regime is provided for by UK legislation, retained EU law and case law. The VAT Act 1994 implemented the Directive. Schedule 9, Group 5, Items 9 and 10 of the Act lists specific types of funds, the management of which is exempted from VAT.

Place of supply

This is important for SIFs management as if the supply is in respect of overseas funds the services are excluded from the exemption (they are outside the scope of UK VAT) when received overseas. This means that there is no output tax on the supply, but unlike exemption, it affords full recovery on input tax incurred in the UK. The perfect VAT outcome.

HMRC Consultation

The technical consultation sets out proposed reform of the legislation that provides for the VAT treatment of fund management. This is required because the fund management industry continues to innovate and introduced new types of funds to the marketplace, and the existing approach has struggled to keep pace with the evolution of the industry and proliferation of fund types.

The purpose of the exercise is to improve the legislative basis of the current VAT treatment of fund management.

Danger?

It is proposed that the following criteria for a fund to be considered a SIF would be legislated for:

a) the fund must be a collective investment

b) the fund must operate on the principle of risk-spreading

c) the return on the investment must depend on the performance of the investments, and the holders must bear the risk connected with the fund; and

d) the fund must be subject to the same conditions of competition and appeal to the same circle of investors as a UCITS (Undertakings for Collective Investment in Transferable Securities), that is funds intended for retail investors

There is a danger that if the exemption is broadened, fund managers which can now recover input tax may be denied so in the future.

If you have any queries, please contact us.

Incoterms: What are they, and how can they be of use for VAT?

By   12 September 2022

VAT – Cross border sales of goods

Incoterms stands for International Commercial Terms.

These are published by the International Chamber of Commerce (ICC) and describe agreed commercial terms. These rules set out the responsibilities of buyers and sellers for the supply of goods under a contract. They are very commonly used in cross-border commercial transactions in order that both sides in a transaction are aware of the contractual position. They help businesses avoid costly misunderstandings by clarifying the tasks, costs and risks involved in the delivery of goods from sellers to buyers. The latest terms were published in 2010 and came into effect in 2011.

The use of Incoterms for assistance for VAT purposes

One of the most difficult areas of providing VAT advice is obtaining sufficient detailed information to advise accurately and comprehensively.  Quite often advisers are given what a client believes to be the arrangements for a transaction. This may differ from the actual facts, or the understanding of the other party in the transaction.

Pragmatically, this uncertainty about the details may be increased if; a number of different people within an organisation are involved, it is a new or one-off type of transaction, there are language difficulties, or communication and documentation is less than ideal. In such cases, incoterms will provide invaluable information which gives clarity and certainty and usually give a sound basis on which to advise. This enables the adviser to establish the place of supply (POS) and therefore what VAT treatment needs to be applied.

So what is this set of pre-defined international contract terms?

They are 11 pre-defined terms which are subdivided into two categories:

Group 1 – Incoterms that apply to any mode of transport are:

EXW – Ex Works (named place)

The seller makes the goods available at their premises. This term places the maximum obligation on the buyer and minimum obligations on the seller. EXW means that a buyer incurs the risks for bringing the goods to their final destination. The buyer arranges the pickup of the freight from the supplier’s designated ship site, owns the in-transit freight, and is responsible for clearing the goods through Customs. The buyer is also responsible for completing all the export documentation.

Most jurisdictions require companies to provide proof of export for VAT purposes. In an EXW shipment, the buyer is under no obligation to provide such proof, or indeed to even export the goods. It is therefore of utmost importance that these matters are discussed with the buyer before the contract is agreed.

FCA – Free Carrier (named place of delivery)

The seller delivers the goods, cleared for export, at a named place. This can be to a carrier nominated by the buyer, or to another party nominated by the buyer.

It should be noted that the chosen place of delivery has an impact on the obligations of loading and unloading the goods at that place. If delivery occurs at the seller’s premises, the seller is responsible for loading the goods on to the buyer’s carrier. However, if delivery occurs at any other place, the seller is deemed to have delivered the goods once their transport has arrived at the named place; the buyer is responsible for both unloading the goods and loading them onto their own carrier.

CPT – Carriage Paid To (named place of destination)

The seller pays for the carriage of the goods up to the named place of destination. Risk transfers to buyer upon handing goods over to the first carrier at the place of shipment in the country of Export. The Shipper is responsible for origin costs including export clearance and freight costs for carriage to named place (usually a destination port or airport). The shipper is not responsible for delivery to the final destination (generally the buyer’s facilities), or for buying insurance. If the buyer does require the seller to obtain insurance, the Incoterm CIP should be considered.

CIP – Carriage and Insurance Paid to (named place of destination)

This term is broadly similar to the above CPT term, with the exception that the seller is required to obtain insurance for the goods while in transit. CIP requires the seller to insure the goods for 110% of their value.

DAT – Delivered At Terminal (named terminal at port or place of destination)

This term means that the seller covers all the costs of transport (export fees, carriage, unloading from main carrier at destination port and destination port charges) and assumes all risk until destination port or terminal. The terminal can be a Port, Airport, or inland freight interchange. Import duty/VAT/customs costs are to be borne by the buyer.

DAP – Delivered At Place (named place of destination)

The seller is responsible for arranging carriage and for delivering the goods, ready for unloading from the arriving conveyance, at the named place. Duties are not paid by the seller under this term. The seller bears all risks involved in bringing the goods to the named place.

DDP – Delivered Duty Paid (named place of destination)

The seller is responsible for delivering the goods to the named place in the country of the buyer, and pays all costs in bringing the goods to the destination including import duties and VAT. The seller is not responsible for unloading. This term places the maximum obligations on the seller and minimum obligations on the buyer. With the delivery at the named place of destination all the risks and responsibilities are transferred to the buyer and it is considered that the seller has completed his obligations.

Group 2 – Incoterms that apply to sea and inland waterway transport only:

FAS – Free Alongside Ship (named port of shipment)

The seller delivers when the goods are placed alongside the buyer’s vessel at the named port of shipment. This means that the buyer has to bear all costs and risks of loss of or damage to the goods from that moment. The FAS term requires the seller to clear the goods for export. However, if the parties wish the buyer to clear the goods for export, this should be made clear by adding explicit wording to this effect in the contract of sale. This term can be used only for sea or inland waterway transport.

FOB – Free On Board (named port of shipment)

FOB means that the seller pays for delivery of goods to the vessel including loading. The seller must also arrange for export clearance. The buyer pays cost of marine freight transport, insurance, unloading and transport cost from the arrival port to destination. The buyer arranges for the vessel, and the shipper must load the goods onto the named vessel at the named port of shipment. Risk passes from the seller to the buyer when the goods are loaded aboard the vessel.

CFR – Cost and Freight (named port of destination)

The seller pays for the carriage of the goods up to the named port of destination. Risk transfers to buyer when the goods have been loaded on board the ship in the country of export. The shipper is responsible for origin costs including export clearance and freight costs for carriage to named port. The shipper is not responsible for delivery to the final destination from the port (generally the buyer’s facilities), or for buying insurance. CFR should only be used for non-containerised sea freight, for all other modes of transport it should be replaced with CPT.

CIF – Cost, Insurance and Freight (named port of destination)

This term is broadly similar to the above CFR term, with the exception that the seller is required to obtain insurance for the goods while in transit to the named port of destination. CIF requires the seller to insure the goods for 110% of their. CIF should only be used for non-containerised sea freight; for all other modes of transport it should be replaced with CIP.

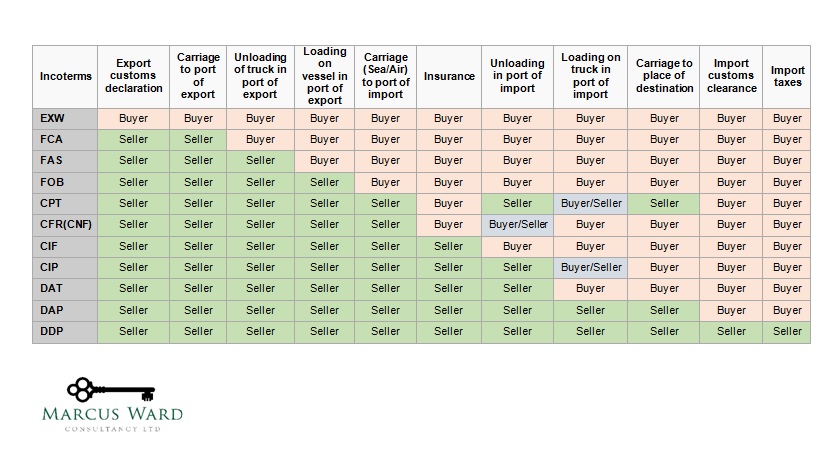
Allocations of costs to buyer/seller via incoterms

Once the Incoterm has been established, the VAT treatment is usually immediately apparent.

Summary Chart

Incoterms Chart

VAT: Place of belonging. The Berlin Chemie A Menarini case

By   13 April 2022

Latest from the courts

The place of belonging of a business or other person is an important tenet of the tax. I have considered this issue at length here and recent case law here.

A recent CJEU case involved a situation where a business had a registered office in one country and, potentially (hence the appeal) a fixed establishment in another.

Background

“Berlin” used a “third party” to receive certain services. Does this entry represent a fixed establishment for Berlin if it has a sufficient degree of permanence and a suitable structure in terms of technical and human resources? If yes, is it is necessary for those human and technical resources to belong to the company receiving the services or whether it is sufficient for that company to have immediate and permanent access to such resources through a related company, of which it is major shareholder?

Technical

The wording of Article 44 of the VAT Directive and Article 11(1) of Implementing Regulation No 282/2011 do not provide any details as to whether human and technical resources must belong to the company that receives the services.

Decision

The CEUJ ruled that, simple control or ownership, of another entity is insufficient to create a fixed establishment for VAT purposes. Consequently, a third party location does not inevitably represent a fixed establishment by dint of control/ownership.

Having made that comment, the court impressed that the decision should be made “in the context of the economic and commercial reality”.

The analysis of the place of belonging should recognise that it is not necessary for the fixed establishment to own the resources, but there should be control over these resources in the same way as an “owner”.  A fixed establishment is characterised by a suitable structure which enables a business to receive and use services supplied to them for their own needs and not by the decision power of a certain structure that businesses have put in place.

Commentary

Although an EU case, it could impact UK businesses who make supplies to EU recipients and particularly, if there is a “network” of offices or business locations in various EU Member States. Overseas suppliers to (potentially) UK business with various business premises and structures will need to recognise this ruling in order to establish the place of supply (and hence what country’s VAT and at what rate to apply).

This decision provides some helpful clarity, which may be summarised as: In principle, a subsidiary does not always create a fixed establishment.